Medicare guide
When and How to Apply for Medicare
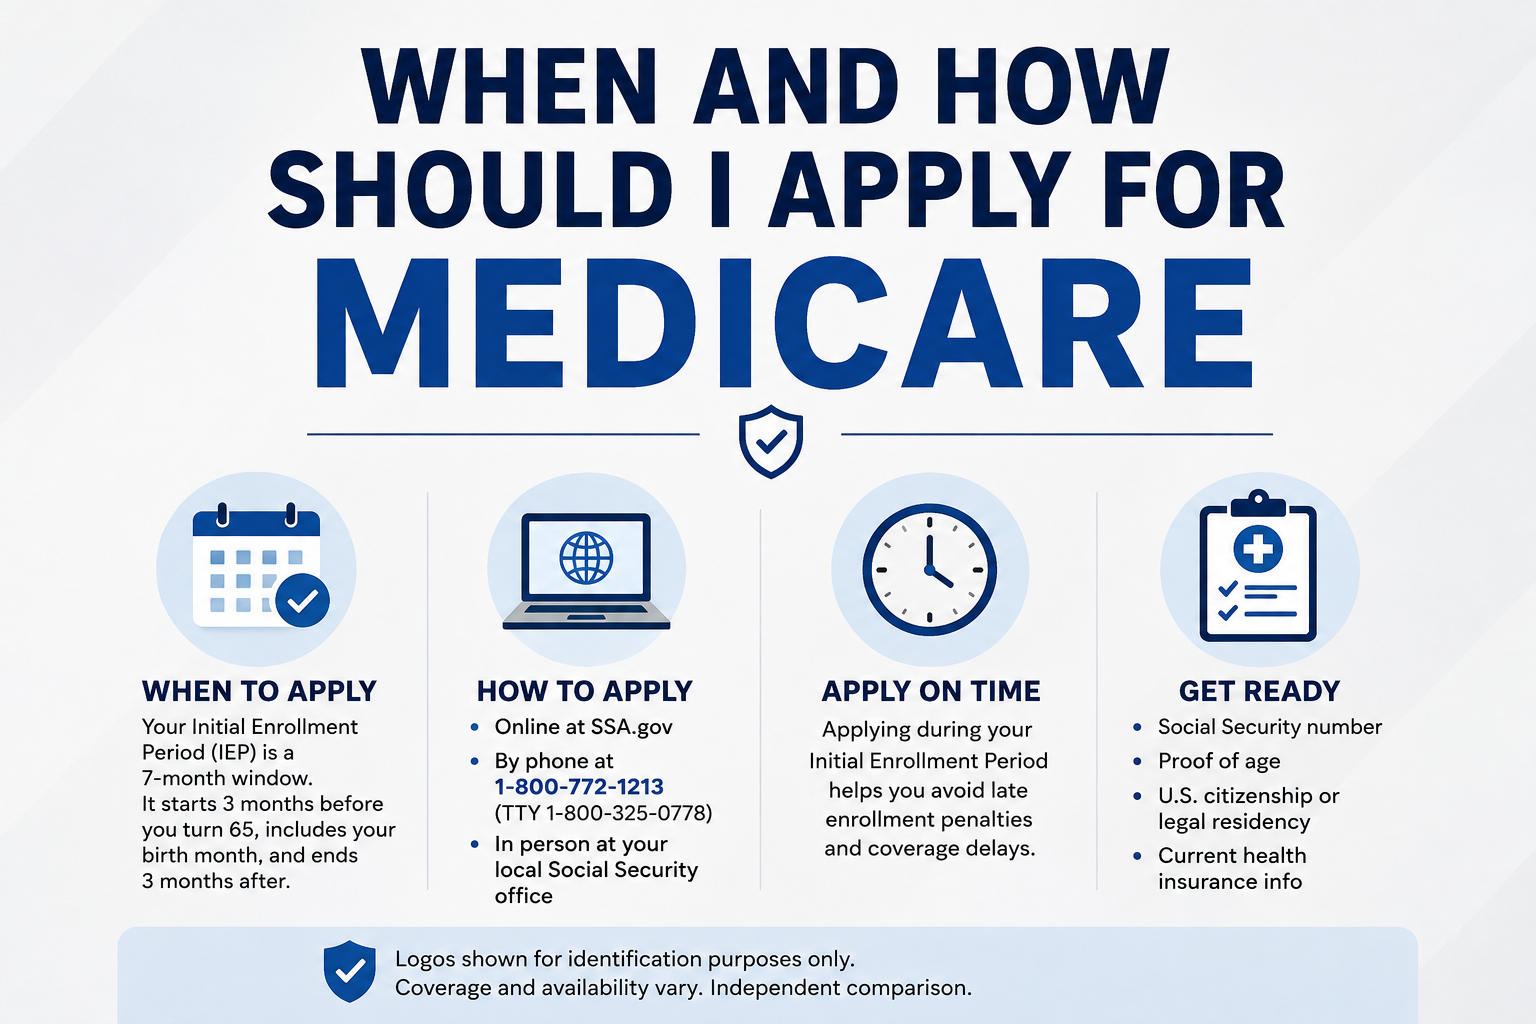
Here’s when and how to apply for Medicare: most people sign up during a seven-month window around their 65th birthday, through Social Security, unless they’re enrolled automatically.
Blake Insurance Group is an independent agency serving clients by phone, email, and online in states where we are licensed; coverage depends on the insurer, the policy, and underwriting.
Request a Medicare plan review
Tell us about your Medicare situation, and a licensed agent will follow up to review plans we offer in your area. Submitting the form does not enroll you in a plan.
Prefer a longer form? You can also request a quote with our Medicare quote form.
If the form does not load, call 888-387-3687, Monday through Friday, 9:00 to 5:00, or email info@blakeinsurancegroup.com.
When to apply
Your Initial Enrollment Period lasts seven months: the three months before the month you turn 65, that month, and the three months after. If you sign up before your birthday month, Part B starts the month you turn 65; if you sign up later, it starts the month after you sign up. If you miss it, the General Enrollment Period runs January 1 to March 31, with coverage starting the month after you sign up, and a late penalty may apply.
How to apply
Social Security says you can apply for Medicare online at ssa.gov, by phone at 1-800-772-1213 (TTY 1-800-325-0778), or at a local office, even if you aren’t ready to start retirement benefits.
You don’t have to claim Social Security to get Medicare. Social Security says you can apply for Medicare online at ssa.gov, by phone at 1-800-772-1213, or at a local office, even if you aren’t ready for retirement benefits. If you aren’t receiving Social Security, Medicare bills you directly; Part B-only premiums are billed every three months, and you can pay online or set up free automatic payments through Medicare Easy Pay.
If you’re still working
You can generally delay Part B without penalty if you have group coverage from current employment, and sign up within eight months after the job or coverage ends. COBRA and retiree coverage don’t count for this.
Medicare charges late penalties if you delay without other qualifying coverage. Medicare.gov says the Part B penalty is 10% for each full 12-month period you could have had Part B but didn’t, usually for as long as you have Part B. The Part D penalty is 1% of the national base beneficiary premium for each month without creditable drug coverage after a 63-day gap; the base premium is $38.99 in 2026 and $41.33 in 2027. You can generally delay Part B without penalty if you have group coverage from current employment, and sign up within eight months after that coverage or employment ends.
Original Medicare costs
| Item | 2026 amount |
|---|---|
| Part A hospital deductible | $1,736 per benefit period |
| Part A coinsurance, days 61–90 | $434 per day |
| Skilled nursing facility, days 21–100 | $217 per day |
| Part B standard premium | $202.90 per month |
| Part B deductible | $283 per year |
| Part D deductible (maximum) | $615 |
| Part D out-of-pocket cap | $2,100 |
| Insulin | No more than $35 for a month’s supply |
Sources: CMS (Nov. 2025, Apr. 2025) and Medicare.gov. 2027 Part A and B amounts had not been announced as of Oct. 22, 2026; CMS usually publishes them in mid-November. Higher-income beneficiaries pay more for Parts B and D.
When you can enroll or switch
| Period | When | What you can do |
|---|---|---|
| Initial Enrollment Period | 7 months around your 65th birthday month | Sign up for Parts A and B, and join a plan |
| Annual Open Enrollment | October 15 – December 7 | Join, switch, or drop Medicare Advantage or drug plans; coverage starts January 1 |
| Medicare Advantage Open Enrollment | January 1 – March 31 | One change: switch MA plans or return to Original Medicare (and add a drug plan) |
| General Enrollment Period | January 1 – March 31 | Sign up for Parts A and B if you missed your IEP; penalties may apply |
| Special Enrollment Periods | After qualifying events | For example, moving or losing employer coverage |
| Medigap Open Enrollment | 6 months from the first month you have Part B and are 65+ | Buy any Medigap policy sold in your state without health questions |
Source: Medicare.gov, October 2026.
Medigap basics
Medigap policies are standardized and sold by private insurers to help pay Original Medicare’s deductibles, coinsurance, and copays. The lettered plans are A, B, C, D, F, G, K, L, M, and N, and a plan with the same letter has the same basic benefits from any company. Plans C and F aren’t available to people new to Medicare on or after January 1, 2020; Plans D and G offer the same benefits except the Part B deductible. Medigap doesn’t work with Medicare Advantage and generally doesn’t include drug coverage, so most people pair it with a Part D plan.
| Item | 2026 | 2027 |
|---|---|---|
| Plan K out-of-pocket limit | $8,000 | $8,360 |
| Plan L out-of-pocket limit | $4,000 | $4,180 |
| High-deductible Plan F, G (and J) deductible | $2,950 | $3,050 |
Sources: Medicare.gov and CMS notices, October 2025 and October 2026.
Types of Medicare Advantage plans
| Type | How it works |
|---|---|
| HMO | Generally in-network care only, except emergencies, urgent care, and out-of-area dialysis; referrals usually required |
| HMO-POS | Like an HMO, but some out-of-network services allowed at higher cost |
| PPO | Out-of-network care allowed at higher cost; no referrals needed |
| PFFS | See any Medicare-approved provider that accepts the plan’s terms |
| SNP | Limited to people with Medicaid, certain chronic conditions, or institutional care; includes drug coverage |
| MSA | High-deductible plan with a medical savings account; no network; separate drug plan needed |
Source: Medicare.gov. Medicare Advantage plans often require prior authorization for some services.
Out-of-pocket limits
Medicare Advantage plans must cap in-network out-of-pocket costs for Part A and B services. For 2026, KFF reports the federal limit is $9,250 in network and $13,900 combined for in- and out-of-network services in PPOs, and that the average plan’s in-network limit is about $5,421. Original Medicare has no out-of-pocket cap, which is one reason people pair it with Medigap.
How agents help, and the rules they follow
An independent agent appointed with several insurers can compare Medicare Advantage, Medigap, and Part D options available in your area, check your doctors and prescriptions against plan networks and drug lists, and help again each fall during Open Enrollment. Agents are paid by the insurers, so you don’t pay a fee for their help. Medicare.gov, 1-800-MEDICARE, and your State Health Insurance Assistance Program (SHIP) also give free, unbiased help; the national SHIP line is 877-839-2675.
Federal rules shape how agents work. Third-party marketing organizations that represent more than one Medicare Advantage organization must give a disclaimer explaining that they don’t offer every plan in your area. Agents must agree with you on a Scope of Appointment, the products you want to discuss, before a sales appointment; a CMS rule effective June 1, 2026 removed the old 48-hour waiting period. And under a 2024 CMS rule, your personal information can be shared with another marketing organization only with your prior express written consent for each recipient.
Avoiding Medicare scams
Medicare.gov says Medicare will never call you to sell you anything or visit you at your home, and that it calls for personal information only in limited cases, such as returning your call. Don’t join a plan over the phone unless you called and asked for help, and don’t give your Medicare or Social Security number to anyone who contacts you unexpectedly. The FTC adds that Medicare sends new cards automatically and for free.
Report suspected fraud to 1-800-MEDICARE (1-800-633-4227) or the HHS Office of Inspector General at 1-800-HHS-TIPS (1-800-447-8477). Medicare Advantage and Part D members can also call the I-MEDIC at 1-877-772-3379.
What Original Medicare doesn’t cover
- Eye exams for prescription eyeglasses
- Most dental care, such as cleanings, fillings, extractions, and dentures
- Hearing aids and exams for fitting them
- Non-medical long-term care (custodial care)
- Routine physical exams
- Cosmetic surgery
- Massage therapy
- Concierge care
- Care from providers who have opted out of Medicare, except emergencies
- Most care outside the United States
Checking a plan and insurer
- Networks. Confirm your doctors and hospitals are in the plan’s network.
- Drugs. Check each prescription on the plan’s formulary and its tier.
- Costs. Compare premiums, deductibles, copays, and the out-of-pocket maximum.
- Agent license. Confirm the agent is licensed in your state through your state insurance department.
- Star Ratings. Review the plan’s rating in Medicare.gov’s plan compare tool.
What an independent agency does
An independent insurance agency is licensed to sell policies from several insurance companies. Instead of quoting one company's products, an independent agent can compare options from the insurers the agency represents, explain the differences in coverage, and help you re-shop at renewal. The insurance company, not the agent, makes underwriting and claim decisions.
Blake Insurance Group is an independent agency. We work with clients by phone, email, and online in states where we are licensed, and we will tell you which insurers we can quote for your situation.
How we work
Blake Insurance Group serves clients by phone, email, and online in states where we are licensed. The insurers and plans we can offer depend on our appointments and your location; a company named on this page may not be available through us.
How to verify an insurer or agency
Before buying through any website or app, confirm who is selling you the policy and who will issue it:
- Find the licensed agency or insurer named in the site's footer, terms, or license page.
- Look up the agency or producer on your state insurance department's license search, or through the National Insurance Producer Registry (NIPR).
- Look up the insurer on your state insurance department's company search to confirm it is authorized in your state.
- Save the insurer's name and policy number once issued, since that is who handles claims.
A legitimate service will make this information easy to find. Be cautious if you cannot identify the licensed entity.
Sources
We checked the facts on this page against the sources below in October 2026. Plans, prices, and rules change, so confirm current terms before you buy.
- CMS: Medicare Advantage and Part D expected to remain stable in 2027 (Sep. 28, 2026)
- KFF: The average Medicare beneficiary has 28 MA-PD plan options for 2027 (Oct. 2026)
- KFF: Medicare Advantage plan availability for 2027 (Oct. 2026)
- CMS: 2027 Medicare Advantage and Part D Star Ratings (Oct. 2026)
- Medicare.gov: Compare Medicare Advantage plan types
- KFF: Medicare Advantage out-of-pocket limits
- Medicare.gov: Joining a health or drug plan
- Medicare.gov: Special Enrollment Periods
- CMS: 2026 Medicare Parts A & B premiums and deductibles (Nov. 2025)
- Medicare.gov: What Original Medicare doesn't cover
- 42 CFR 422.2267: Required materials and content (TPMO disclaimer)
- 42 CFR 423.2264: Beneficiary contact and Scope of Appointment
- ACL: State Health Insurance Assistance Program (Mar. 2026)
- Medicare.gov: Medicare fraud
- CMS: Contract Year 2027 Medicare Advantage and Part D final rule (Apr. 2026)
- Medicare.gov: Your Medicare in 2027: What's new and changing (Sep. 2026)
- SSA: Medicare publication EN-05-10530 (June 2026)
- SSA: Sign up for Medicare
- Medicare.gov: When does Medicare coverage start?
- Medicare.gov: Avoid late enrollment penalties
What to have ready for a Medicare review
These details help an agent quote accurately.
- Medicare card. Your Medicare number and Part A and B start dates.
- Doctors. Names of doctors and hospitals you want to keep.
- Prescriptions. Drug names, doses, and pharmacies.
- Current coverage. Any plan, employer, or Medicaid coverage you have.
- ZIP code. Plans differ by county.
When and How to Apply for Medicare FAQs
When is Medicare Open Enrollment?
October 15 to December 7, for coverage starting January 1.
Have 2027 Part A and B costs been announced?
Not as of October 23, 2026; CMS usually announces them in mid-November.
Where can I get free, unbiased help?
Your State Health Insurance Assistance Program at 877-839-2675, or 1-800-MEDICARE.
Does Medicare call people to sell plans?
No. Medicare.gov says Medicare will never call you to sell you anything.
Is an agent’s help free?
Yes. Agents are paid by insurers.
Related guides
Important information
Independent agency. Blake Insurance Group LLC is an independent insurance agency. Licensed insurance producer NPN 16117464. Licensed states: AZ, AL, TX, CA, NY, OH, FL, NC, VA, GA, OK, NM, IA, KS, MI, NE, SC, SD, WV, IL, NJ, PA, TN, and WA. Which insurance companies we can quote depends on our current appointments, the product, and your state. Mentioning a company on this page does not mean we represent it.
Medicare disclaimer. We do not offer every plan available in your area. Any information we provide is limited to those plans we do offer in your area. Please contact Medicare.gov, 1-800-MEDICARE (TTY users 1-877-486-2048), or your local State Health Insurance Assistance Program (SHIP) to get information on all of your options.
Medicare figures. Costs, limits, and rules on this page were checked against CMS, Medicare.gov, and the other listed sources in October 2026. 2027 Part A and B amounts had not been announced. Confirm current figures at Medicare.gov.
Company names. Company names are trademarks of their owners. Blake Insurance Group isn’t affiliated with the companies described unless a partner link says so, and a company named here may not be available through us. Plan availability, ratings, and benefits vary by county and can change; facts were checked in October 2026.
Coverage terms. Descriptions are general. The policy contract controls what is covered.
Availability. Coverage, prices, and eligibility vary by company, state, and applicant, and are subject to underwriting. The issued policy controls.
Your next step
Request a review, and a licensed agent will compare Medicare plans available to us in your area. You can also use Medicare.gov or 1-800-MEDICARE to see all options.




