North Carolina • Car insurance
Auto Insurance in North Carolina: New Minimums and How Pricing Works
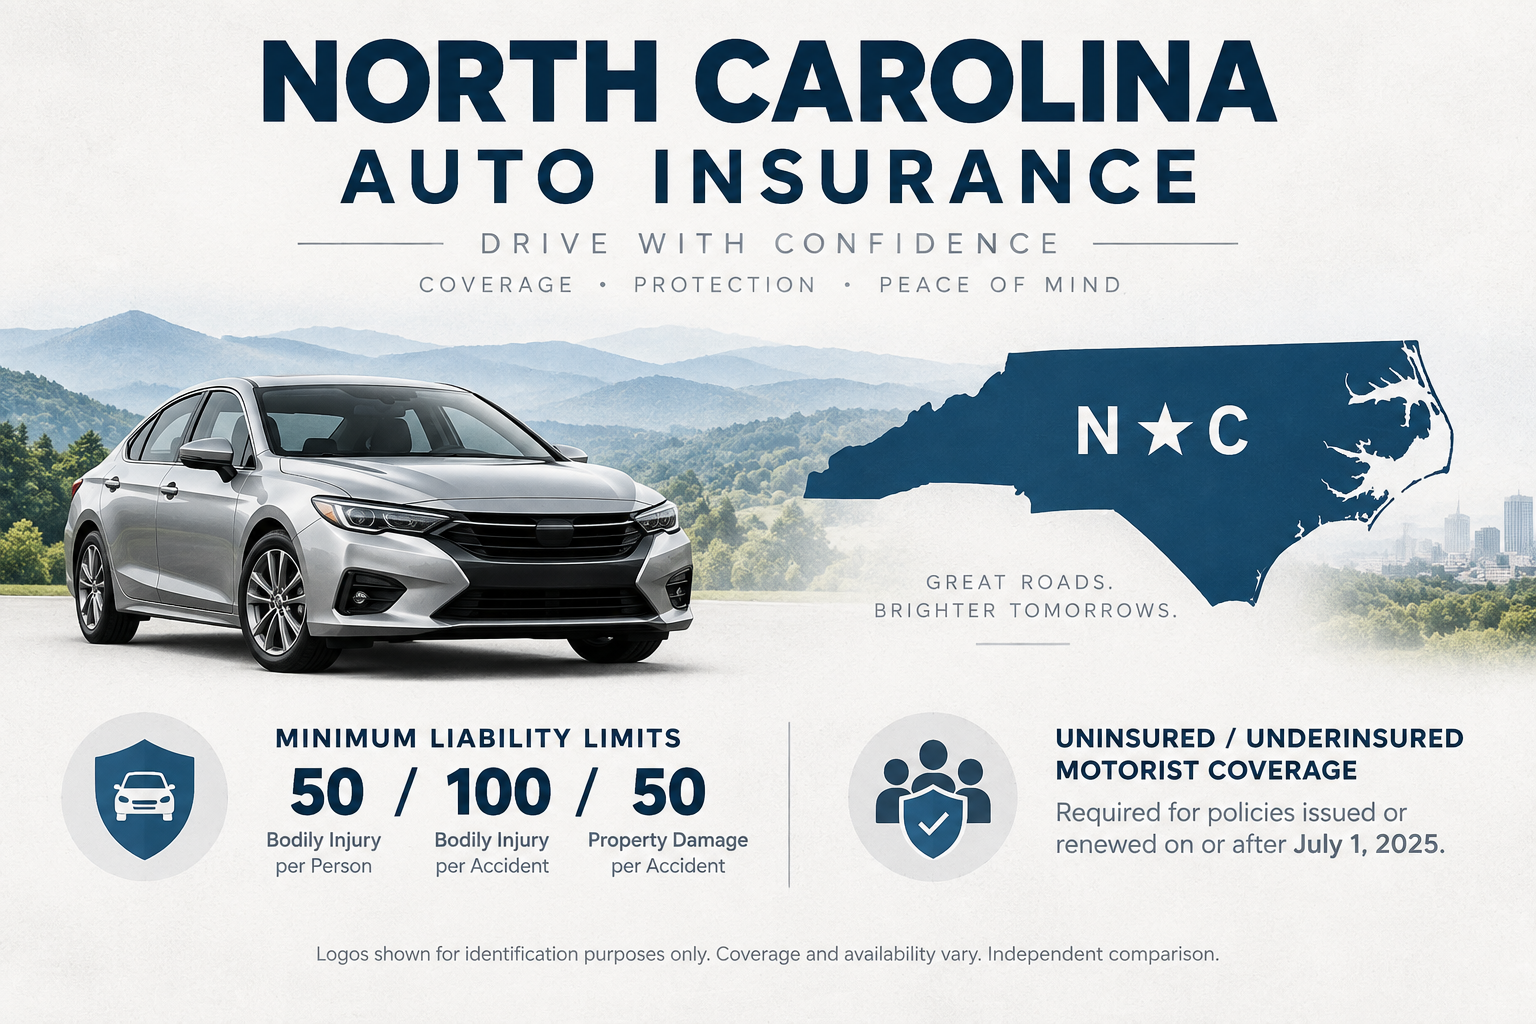
Auto insurance in North Carolina changed on July 1, 2025, when minimum liability limits rose to 50/100/50 with matching uninsured/underinsured motorist coverage. North Carolina also prices insurance differently from most states, through a Rate Bureau and a point system tied to your driving record.
This guide covers North Carolina's requirements, the coverage decisions that matter most, what makes North Carolina different, and how to compare quotes. See also our North Carolina auto insurance and North Carolina car insurance costs guides. Blake Insurance Group is an independent agency; a licensed agent can compare options available to us in North Carolina.
Compare North Carolina car insurance
Tell us about your drivers and vehicles, and a licensed agent will follow up with options available to us. Submitting the form does not bind coverage.
If the form does not load, call 888-387-3687, Monday through Friday, 9:00 to 5:00, or email info@blakeinsurancegroup.com.
North Carolina minimum requirements
| Coverage | Minimum |
|---|---|
| Bodily injury liability | $50,000 per person / $100,000 per accident (from July 1, 2025) |
| Property damage liability | $50,000 per accident |
| Uninsured / underinsured motorist | Required at matching limits |
Source: Insurance Information Institute state table and state regulator guidance. Requirements can change.
The 2025 law changes
For policies written or renewed on or after July 1, 2025, North Carolina's minimum liability limits rose from 30/60/25 to 50/100/50, and uninsured and underinsured motorist coverage must match. The law also changed how surcharges apply to newly licensed drivers. If your policy renewed before that date, your next renewal will reflect the new minimums.
How North Carolina prices insurance
The North Carolina Rate Bureau files base rates for insurers, so prices tend to be more uniform than in many states, but insurers still compete on discounts, deviations, and service. Higher-risk drivers can be placed through the North Carolina Reinsurance Facility, which keeps coverage available. The state's Safe Driver Incentive Plan adds surcharges for violations and at-fault accidents.
Contributory negligence
North Carolina follows contributory negligence: if you are found even slightly at fault, you may be barred from recovering damages from the other driver. Your own collision, medical payments, and UM/UIM coverage matter more as a result.
How costs compare
In NAIC data for 2022, the average annual auto insurance expenditure in North Carolina was $840.24, ranking 42nd of 51 (including D.C.), compared with $1,126.79 nationally. Averages blend liability-only and full-coverage policies and are not quotes. See our auto insurance rates by state guide.
Hurricanes and comprehensive
Hurricanes and tropical storms bring flooding to the coast and, as Helene showed in 2024, to the mountains. Comprehensive coverage pays for flood and wind damage to your car. Buy it before storm season, since insurers typically suspend new coverage when a hurricane threatens.
Coverage terms to match on every quote
| Coverage | What it pays for | What to match |
|---|---|---|
| Bodily injury liability | Injuries you cause to others | Per-person and per-accident limits, such as 100/300 |
| Property damage liability | Damage you cause to others' property | Same limit on both quotes, such as $100,000 |
| Uninsured/underinsured motorist | Your injuries when the at-fault driver lacks enough coverage | Same limits; ideally equal to your liability limits |
| Collision | Damage to your car from a crash | Same deductible |
| Comprehensive | Theft, fire, hail, flood, animal strikes, glass | Same deductible; note any glass option |
| Medical payments or PIP | Medical costs for you and passengers | Same limit; PIP rules depend on your state |
| Rental and roadside | Transportation during repairs; towing | Same daily and total limits |
Limits shown are examples, not recommendations. State minimum requirements differ.
Three coverage levels compared
| Level | Liability limits | Who it may fit | Trade-off |
|---|---|---|---|
| State minimum | 50/100/50 | Drivers with few assets who need the lowest legal price | Little protection after a serious crash |
| Middle | 100/300/100 | Many households with savings or a home | Moderately higher premium |
| Higher | 250/500/100 or more | Homeowners and drivers who want an umbrella policy | Highest premium, strongest protection |
Examples only, not recommendations. Add UM/UIM at matching limits where possible.
Moving from the minimum to a middle level often costs less than people expect, because liability premiums do not rise in proportion to limits. Ask for both prices before deciding.
Ways to lower your premium
- Compare at least three quotes with identical coverage every year or two, and whenever your premium jumps at renewal.
- Raise collision and comprehensive deductibles to an amount you could pay tomorrow without strain.
- Drop collision and comprehensive on an older car only when the car's value is low enough that you could replace it yourself.
- Ask about every discount: multi-policy, multi-vehicle, good student, defensive driving, paperless, paid-in-full, and safety equipment.
- Try a driving-data program if you drive carefully and are comfortable sharing driving data. See usage-based insurance.
- Keep continuous coverage. Even a short lapse can raise future rates.
- Report accurate mileage. Lower annual mileage can mean a lower premium.
- Bundle auto with renters or homeowners insurance where the combined price is lower.
Discounts to ask about
| Discount | Who it may fit | What to ask |
|---|---|---|
| Multi-policy | Households with renters or home insurance | How much it saves on the total, not just auto |
| Multi-vehicle | Households with two or more cars | Whether every car must be on one policy |
| Good student | Students with qualifying grades | Grade requirements and proof needed |
| Defensive driving | Drivers who complete an approved course | Which courses qualify and how long the discount lasts |
| Telematics | Careful, low-mileage drivers | Whether the program can raise your rate |
| Paid in full and autopay | Drivers who can pay upfront | How installment fees compare |
| Safety and anti-theft | Newer vehicles with safety features | Which features qualify |
Discount names, amounts, and availability vary by insurer and state.
Coverage you should think twice about cutting
Some coverage cuts save very little and expose you to large losses. Be cautious about:
- Buying only the state minimum liability. Minimum limits can be exhausted by a single serious injury, leaving you personally responsible for the rest.
- Rejecting uninsured motorist coverage. It protects you when the at-fault driver has no insurance or too little. See uninsured and underinsured motorist coverage.
- Dropping collision on a financed car. Lenders and lessors usually require it.
- Letting the policy lapse between vehicles or during a move.
How insurers set your price
Most insurers price a policy using your driving record, years licensed, age where allowed, the vehicle, where it is garaged, annual mileage, coverage limits, deductibles, prior insurance history, and, where state law permits, a credit-based insurance score. Each insurer weighs these factors differently, which is why quotes for the same driver can differ by hundreds of dollars. Improving the factors you control, especially your record and continuous coverage, pays off over several renewals.
Payment plans and fees
How you pay can change your total cost. Many insurers charge installment fees for monthly payments, and some offer discounts for paying the full term upfront, enrolling in automatic payments, or going paperless. If paying in full is not possible, ask which payment plan has the lowest fees. Missing a payment can cancel your policy and create a lapse, which raises future rates, so set up reminders or autopay.
If you are considered high risk
If several insurers decline you because of violations, accidents, a lapse, or a DUI, you still have options. Many insurers specialize in higher-risk drivers, and every state has a residual market plan for drivers who cannot find coverage in the voluntary market. Prices are higher, but keeping coverage continuous and your record clean will usually bring rates down over three to five years. If a court or the motor vehicle agency requires an SR-22 or similar filing, see our SR-22 insurance and high-risk auto insurance pages.
When an agent may help
Online tools work well for simple situations. A conversation with a licensed agent may be more useful when:
- You have a teen driver, several vehicles, or drivers with recent accidents or violations.
- You need an SR-22 or other state filing. See our SR-22 insurance page.
- You use a vehicle for rideshare, delivery, or other business purposes.
- You own a home, rental property, or significant savings and want liability limits that work with an umbrella policy.
- You have had a claim denied or a policy nonrenewed and need help understanding your options.
An agent can also explain differences in policy wording that are hard to see on a results page.
Switching insurers without a gap
If a new quote is lower, switch carefully so you are never uninsured:
- Confirm the final price after the insurer verifies your information.
- Set the new policy to start on or before the date the old one ends.
- Give the new insurer your lender or lessor information if the vehicle is financed.
- Save your new ID cards and declarations page.
- Cancel the old policy effective the same day, and ask about any refund of unused premium.
- If you have an SR-22, confirm the new insurer files it before the old filing ends.
What to have ready for a North Carolina quote
These details help produce accurate quotes.
- Driver details. License numbers and dates of birth for every household driver.
- Vehicle VINs. And annual mileage for each vehicle.
- Driving history. Accidents and violations in the past three to five years.
- Current declarations page. To match limits and deductibles.
- Garaging address. Where each vehicle is kept in North Carolina.
North Carolina auto insurance FAQs
What is the minimum car insurance in North Carolina?
50/100/50 liability plus matching UM/UIM, since July 1, 2025.
What is the NC Rate Bureau?
The organization that files base auto rates for insurers.
What is SDIP?
The Safe Driver Incentive Plan, which adds surcharges for violations.
Is North Carolina a no-fault state?
No. It follows contributory negligence.
Is NC car insurance cheap?
North Carolina averaged $840.24 in 2022, below the national average.
Does comprehensive cover flooding?
Yes, subject to the deductible.
Who regulates insurance in North Carolina?
The North Carolina Department of Insurance.
How often should I compare?
Every year or two.
Related guides
Important information
Independent agency. Blake Insurance Group LLC is an independent insurance agency. Licensed insurance producer NPN 16117464. Licensed states: AZ, AL, TX, CA, NY, OH, FL, NC, VA, GA, OK, NM, IA, KS, MI, NE, SC, SD, WV, IL, NJ, PA, TN, and WA. Which insurance companies we can quote depends on our current appointments, the product, and your state. Mentioning a company on this page does not mean we represent it.
Legal requirements. State requirements summarized here are general information as of October 2026 and can change. This page is not legal advice; confirm current rules with your state's insurance regulator or motor vehicle agency.
Availability. Coverage, prices, discounts, and eligibility vary by insurer, state, and applicant, and are subject to underwriting. The issued policy controls.
Your next step
Request a quote, and a licensed agent will compare North Carolina options available to us using the coverage you choose.
Share This




Customer Reviews
Blake Insurance Group
Phone: (888) 387-3687
Email: info@blakeinsurancegroup.com
Hours: Mon-Fri 9:00 am to 5:00 pm
Sat-Sun: Closed

Blake Nwosu
Owner & Principal Agent