Classic car insurance cost · Updated September 2026
How Much Is Classic Car Insurance? Typical Costs and What Changes Your Price
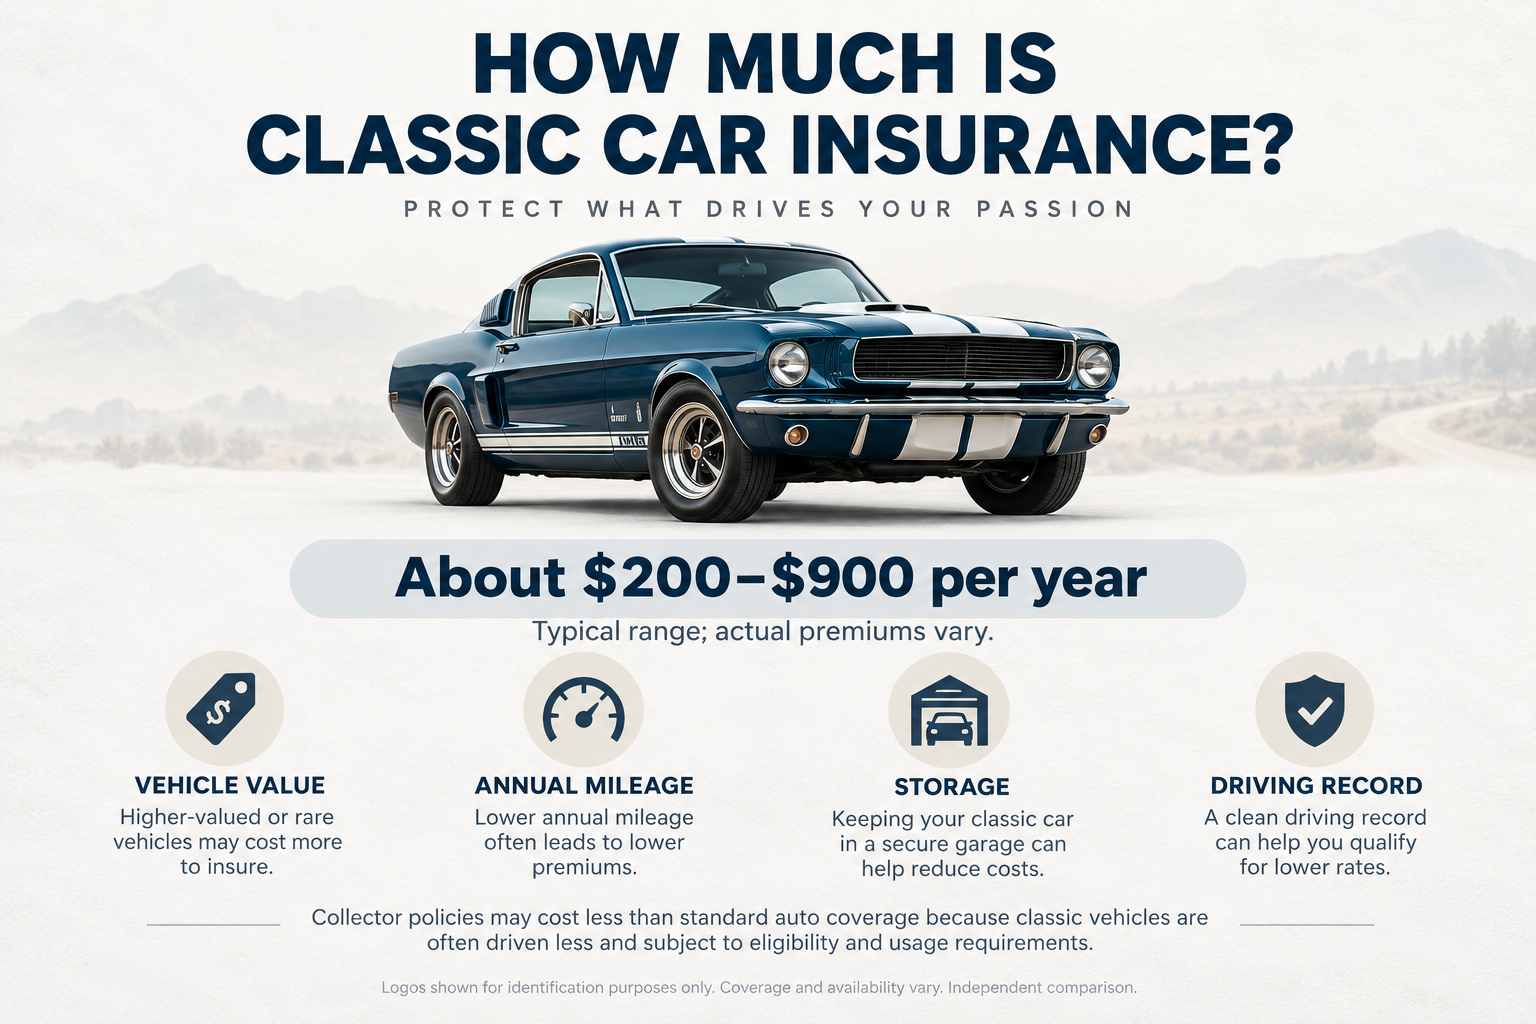
Image unavailable. Continue below for the full guide.
How much is classic car insurance? For many owners, a classic car policy costs a few hundred dollars a year. CNBC Select cites a typical range of $200 to $600 a year, and other 2026 guides report roughly $200 to $900. Your price depends mostly on the agreed value you insure, how much you drive, where the car is stored, and who drives it.
Classic car insurance is usually cheaper than a regular auto policy because collector cars are driven less and stored carefully. That lower price comes with rules, such as mileage limits, garage requirements, and a separate everyday car. This guide explains typical costs, the factors that move your premium up or down, how major collector programs differ on price-related features, and ways to save without cutting the coverage you need.
Reviewed by Blake Nwosu, owner and principal agent, Blake Insurance Group LLC · Updated September 2026
Our classic auto quote form takes a few minutes. We review your car, how you drive it, and where it's stored, then help you compare the collector car options available to you. Availability depends on underwriting and your state.
The short answer
Typical classic car insurance costs in 2026
There isn't one price for classic car insurance, because every policy is built around an agreed value you and the insurer set together. Still, published ranges give a useful starting point.
| Source | What it reports |
|---|---|
| CNBC Select | A classic car policy typically costs $200 to $600 a year, citing Baily Insurance Agency; classics are typically 40% to 50% cheaper to insure than standard daily-use vehicles |
| InsuredBetter | Classic car insurance averages about $200 to $900 a year, or about $17 to $75 a month |
| Hagerty | Customers save $244 on average versus daily driver insurance, and premiums are up to 21% lower on average, based on 2022 Hagerty consumer data for single-car quotes of $5,000 and under |
| J.C. Taylor | Antique auto insurance often costs up to 40% less than a standard auto policy |
| American Collectors | Advertises savings of up to 40% compared with regular auto insurance |
These figures are averages and marketing claims, not quotes. A $15,000 weekend cruiser in a locked garage will usually cost far less than a $250,000 exotic driven to events across the country. The only way to know your price is to quote your car with the value, limits, and deductible you actually want.
Premiums also change with state rules. States set minimum liability limits and required coverages such as personal injury protection or uninsured motorist coverage, and those requirements apply to classic cars too.
How pricing works
Why classic car insurance usually costs less than regular auto insurance
Collector car programs price for lower risk. The Insurance Information Institute notes that classic policies often limit use, may include mileage limits, and usually require the car to be stored in a locked, enclosed structure. MarketWatch notes that collector cars are driven fewer miles, used for occasional pleasure driving or shows, and stored securely, which lowers the insurer's risk.
The trade-off is eligibility. Most programs require a separate everyday vehicle, a clean driving record, and a car in good condition. If you plan to drive a classic every day, a collector policy usually won't fit, and a standard auto policy will price the car very differently. Our classic car insurance vs regular auto insurance guide explains the differences.
There's also a value difference. Standard auto policies often pay actual cash value after a total loss, which subtracts depreciation. Classic programs usually pay an agreed value set in advance. That's better protection for an appreciating car, but it also means your premium grows as the agreed value grows.
Example of how the deductible affects a payout: if your car is insured for an agreed value of $40,000 and your policy has a $250 deductible that applies to a covered total loss, the payout would be $39,750. With a $0 deductible, it would be $40,000. Your policy wording controls how deductibles apply.
Rating factors
What changes the cost of classic car insurance
Collector programs look at the car, the driver, and how the car is used and stored. These are the factors most likely to move your premium.
| Factor | Why it matters | What you can do |
|---|---|---|
| Agreed value | The higher the value, the more the insurer could pay after a total loss | Insure for a supported market value; don't underinsure, and update as the car appreciates |
| Annual mileage and use | More miles and broader use raise risk | Choose a mileage plan that fits real driving; avoid commuting use unless the policy allows it |
| Storage | Locked, enclosed garages reduce theft and weather losses | Keep the car in a locked garage; ask about garage security discounts |
| Driving record | Violations and at-fault accidents raise risk and can disqualify a driver | Keep a clean record; list only drivers who will use the car |
| Driver age and experience | Some programs require drivers to be 25 or older or have years of licensed experience | Check each program's driver rules before applying |
| Deductible | A higher deductible usually lowers the premium | Pick a deductible you can comfortably pay |
| Liability limits | Higher limits cost more but protect your assets | Match limits to your everyday auto and umbrella policies |
| Location | State rules and local theft, weather, and claim costs affect price | Ask how your ZIP code and storage location are rated |
| Vehicle type and modifications | Exotics, race-derived cars, and heavy modifications can price higher | Document modifications and receipts to support the value |
| Number of cars | Multi-vehicle policies often earn discounts | Quote your whole collection together |
Specialist repair costs matter too. The Insurance Information Institute notes that specialist repair rates for vintage cars can be two or three times the cost of a typical body shop repair, which is why agreed value and shop choice are worth paying for.
Program features
How major classic car programs compare on price-related features
Premiums aren't published, but program features that affect price are. Here's what major collector programs say publicly about mileage and deductibles. Use it to choose which programs to quote.
| Program | Mileage and use | Deductible approach | Notable included extras |
|---|---|---|---|
| Hagerty | No published cap; flexible pleasure use, no commuting | Varies by policy | $750 spare parts; auto show medical up to $10,000 |
| American Modern | Plans of 1,000, 3,000, and 6,000 miles listed by agents | Options reported from $0 to $10,000 | Spare parts, towing, travel loss, disaster relocation |
| Grundy | Unlimited miles for pleasure driving | Drops 25% per claim-free year to $0 | $750 parts and tools; up to $600 trip interruption |
| Heacock Classic | Limited annual miles; MarketWatch lists 6,000 | No deductible in most cases | $2,000 spare parts; $200 towing and labor |
| J.C. Taylor | Hobby use within your policy's annual limit | $0 physical damage in most states | Canada coverage; new additions at purchase price |
| American Collectors | Low-mileage and tailored plans | Customizable | Inflation Guard; new purchases up to $100,000 for 30 days |
Want the details behind each row? See our comparisons of Hagerty vs American Modern and Grundy vs Heacock Classic, or our overview of how to compare classic car insurance companies.
Lower your premium
How to lower the cost of classic car insurance
You can often lower your premium without giving up the protection that matters.
- Match mileage to reality. If you drive 1,500 miles a year, a lower mileage plan may cost less than a flexible or unlimited option.
- Store the car securely. A locked, enclosed garage is required by most programs and some offer garage security discounts.
- Choose a sensible deductible. A higher deductible usually lowers the premium; some programs offer $0 or shrinking deductibles.
- Insure several cars together. Multi-vehicle discounts are common with collector programs.
- Keep a clean record. Programs such as American Collectors publish specific violation limits.
- Bundle where it makes sense. Some programs offer multi-policy discounts with home or other policies.
- Keep the value current. An accurate agreed value avoids paying for too much coverage or being underpaid after a loss.
Don't cut liability limits just to save a few dollars. A classic car can still cause a serious accident, and your liability coverage protects your savings and home.
Take the next step
How to get an accurate classic car insurance quote
An accurate quote starts with accurate details. Blake Insurance Group is an independent agency. We'll help you set a supported agreed value and compare the collector programs available to you in your state.
- Gather photos, receipts, and any appraisal that support the value you want to insure.
- Estimate your annual miles and list the events, tours, or trips you plan.
- Confirm where the car is parked and whether the space is locked and enclosed.
- List every household driver and the everyday vehicle each one uses.
- Choose liability limits that match your everyday auto policy.
- Compare quotes with the same value, limits, and deductible.
Our classic auto quote form takes a few minutes. We review your car, how you drive it, and where it's stored, then help you compare the collector car options available to you. Availability depends on underwriting and your state.
Common questions
Frequently asked questions
How much is classic car insurance per month?
InsuredBetter reports roughly $17 to $75 a month. Your price depends on the agreed value, mileage, storage, drivers, and state.
Is classic car insurance cheaper than regular car insurance?
Usually, yes. CNBC Select reports classics are typically 40% to 50% cheaper to insure than daily-use vehicles, because they're driven less and stored carefully.
Does a higher agreed value raise my premium?
Yes. The agreed value is the amount the insurer agrees to pay after a covered total loss, so a higher value usually means a higher premium.
Can I use classic car insurance for a daily driver?
Usually not. Most collector programs require a separate everyday vehicle and exclude commuting and errands.
What's the cheapest classic car insurance?
There's no single cheapest company. The lowest price depends on your car and use. Compare several programs with identical coverage.
Do I need an appraisal to get a quote?
Not always. Some programs set value from photos and market data, and may ask for an appraisal for higher values. Receipts and photos help support your value.
Keep researching
Related guides and official sources
These Blake Insurance Group guides cover related coverage questions.
We checked the rules on this page against these official and industry sources in September 2026:
- CNBC Select: Best classic car insurance companies of 2026 (external site)
- InsuredBetter: Classic car insurance 2026 cost and coverage (external site)
- Hagerty: Compare Hagerty vs daily driver insurance (external site)
- J.C. Taylor: Antique auto insurance (external site)
- American Collectors Insurance: Collector car insurance (external site)
- Insurance Information Institute: Insuring your classic car (external site)
- MarketWatch Guides: Best classic and collector car insurance (external site)
- Classic Automobile Insurance: American Modern collector car program (external site)
- Grundy: Collector vehicle insurance program (external site)
- Heacock Classic: Producer's guide (external site)
Coverage disclosure: Blake Insurance Group LLC is an independent insurance agency. This page compares publicly available program information from each company's website and published reviews as of September 2026. Eligibility, mileage plans, agreed values, deductibles, included extras, and availability are set by each company and its underwriting insurers, vary by state, and can change. This page is general information, not a policy, a quote, or legal advice. Your policy documents control your coverage. Carrier and program names are trademarks of their owners and are used for identification only; this page is not operated by or affiliated with any company compared here.
Find out what your classic will cost to insure
Send us your car details once, and we'll help you compare collector car options so you can see real prices for your car, not just averages.
Reviews are loaded from Google when you click “View reviews.”