Classic car insurance
Agreed Value vs. Stated Value: How Your Car Is Paid After a Total Loss
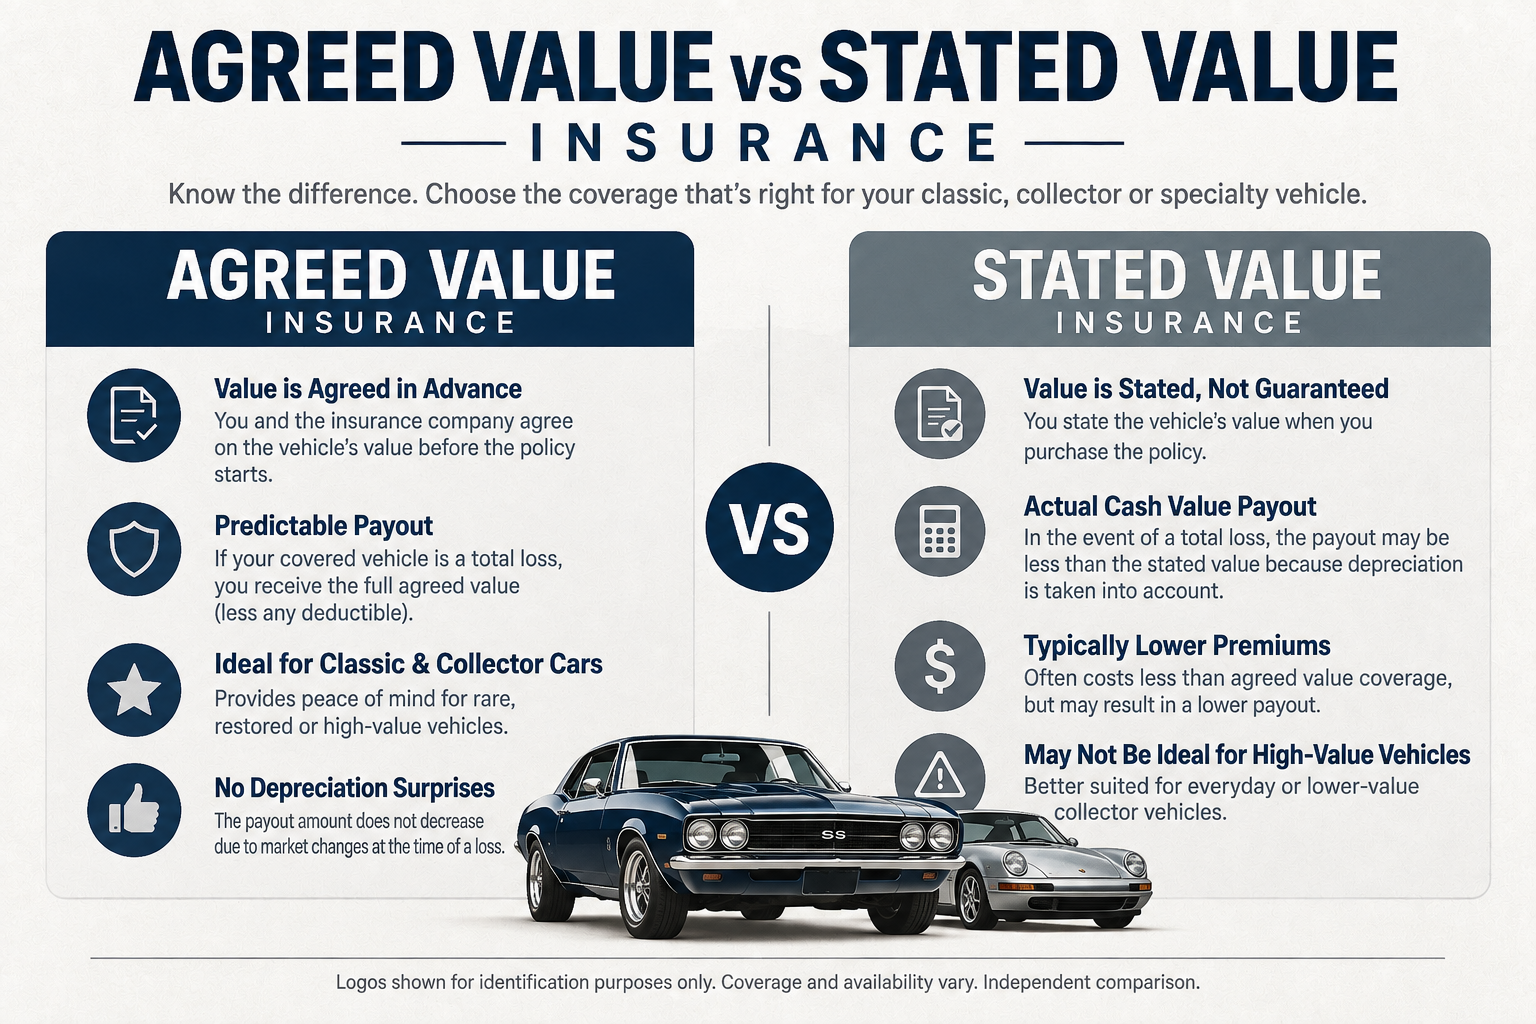
Agreed value vs. stated value is the most important distinction in collector car insurance. Agreed value pays the amount you and the insurer agreed on, minus any deductible, if the car is totaled. Stated value usually pays the lesser of the amount you stated or the car's actual cash value, which can be much less.
Blake Insurance Group is an independent agency; a licensed agent can compare collector vehicle options available to us. This page is general information; eligibility and coverage vary by insurer and state.
Compare collector car coverage
Tell us about your collector vehicle, how you use and store it, and your drivers, and a licensed agent will follow up with options available to us. Submitting the form does not bind coverage.
If the form does not load, call 888-387-3687, Monday through Friday, 9:00 to 5:00, or email info@blakeinsurancegroup.com.
The three valuation methods
| Method | What it pays on a total loss | Typical use |
|---|---|---|
| Agreed value | The amount agreed when the policy was written, minus any deductible | Collector and classic car programs |
| Stated value | Usually the lesser of the stated amount or actual cash value | Some specialty and older-vehicle policies |
| Actual cash value | Market value minus depreciation at the time of loss | Standard auto policies |
General descriptions. Policy wording controls.
An example
Suppose you insure a restored car for $60,000. If it is totaled and the insurer determines its actual cash value is $45,000, an agreed value policy pays $60,000 minus any deductible. A stated value policy that pays the lesser of stated value or actual cash value pays $45,000. A standard policy pays actual cash value, $45,000, minus the deductible.
Why stated value exists
Stated value can cost less and may be offered for older vehicles that do not meet collector program rules. It caps the most you can receive, but it does not guarantee that amount. American Modern, for example, offers a stated value option alongside agreed value; ask exactly how the option pays.
Choosing the right valuation
- Choose agreed value for collectible cars whose value differs from book value.
- Support the value with photos, receipts, and appraisals.
- Review the value every year.
- Read the valuation clause before buying; terms like guaranteed value and agreed value can differ in details.
Classic vs. regular auto insurance
| Feature | Classic car insurance | Regular auto insurance |
|---|---|---|
| Valuation | Agreed or guaranteed value set in advance | Actual cash value, which reflects depreciation |
| Usage | Limited pleasure use, shows, club events; mileage limits common | Unrestricted daily driving |
| Storage | Often requires a locked garage or secure storage | No storage requirement |
| Driver rules | Clean records, minimum ages, and a regular-use vehicle often required | Broad driver eligibility |
| Cost | Often lower for qualifying vehicles because of limited use | Priced for daily exposure |
| Extras | Spare parts, restoration, and show-trip coverage options | Rental, roadside, and new car replacement options |
General comparison. Eligibility rules and coverage options vary by insurer.
Common eligibility rules
Specialty insurers set their own eligibility rules, but common requirements include:
- Vehicle age or status. Many insurers look for vehicles at least 20 to 25 years old, though some cover modern collectibles, exotics, and limited-production vehicles.
- Condition. The vehicle is maintained, restored, or being restored, and is not a daily driver.
- Storage. A locked, enclosed garage or storage unit.
- Regular-use vehicle. Each household driver has another car for daily transportation.
- Driving record. Clean records and minimum driver ages, often 25 or older.
- Usage limits. Pleasure use, club activities, and shows, sometimes with annual mileage caps.
Extras to compare
- Spare parts coverage for parts you store for the vehicle.
- Restoration or under-construction coverage that increases value as work is completed.
- Flatbed towing to protect the vehicle during transport.
- Show and trip coverage, including transport to events.
- Inflation guard that increases agreed value over time.
- Roadside assistance designed for collector vehicles.
Storage and security
Most classic insurers require a locked, enclosed garage, and some accept secure storage facilities. Security measures such as alarms, cameras, battery disconnects, and steering locks reduce theft risk. Check whether the policy covers the car while stored at another location, such as a seasonal storage facility, and tell your insurer if storage changes.
Appraisals and inspections
Many classic insurers set agreed value using your estimate supported by photos, with a professional appraisal required for higher-value vehicles. An appraisal from a recognized appraiser documents condition, originality, and comparable sales. Update it every few years or after significant work. Some insurers inspect vehicles or request additional photos before binding coverage on high-value cars.
Classic car claims
Collector car claims differ from everyday claims. Ask whether you can choose a restoration specialist, how original or reproduction parts are handled, and whether the policy pays for diminished value after repairs. With agreed value coverage, a total loss pays the agreed amount; some insurers let you buy back the salvage. Report claims promptly and document damage thoroughly.
Liability and umbrella for collectors
Collectors often have significant assets, and a serious accident in any vehicle can lead to a large claim. Classic policies include liability, but limits may be modest by default. Ask about higher liability limits, and consider an umbrella policy, checking whether the umbrella insurer requires the classic policy's liability limits to meet a minimum.
Agreed value and how total losses are paid
The most important difference is how a total loss is paid. A regular auto policy pays actual cash value: the market value at the time of loss, minus depreciation, which can be far below what a collector car is worth. Classic policies typically use agreed or guaranteed value, where you and the insurer agree on the car's value when the policy is written, and that amount is paid if the car is totaled, minus any deductible where one applies. Stated value policies are different: they may pay the lesser of the stated amount or actual cash value. Read the valuation wording carefully, and update the agreed value after restoration work or as market values rise. Keep appraisals, receipts, and photos.
Shows, clubs, and transport
Car shows, club rallies, parades, and track-style events are central to collector ownership, but coverage varies. Most classic policies cover driving to and from shows and club events. Racing, timed events, and track days are usually excluded and need separate coverage. When trailering a car to an event, confirm whether the policy covers it during loading, transport, and unloading, and whether the trailer itself is covered.
Specialist programs to compare
| Program | How you buy | Valuation | Usage and mileage |
|---|---|---|---|
| Hagerty | Directly, through independent agents, and, for State Farm Classic+, through State Farm agents | Guaranteed Value (an agreed value approach) | Limited pleasure use; rules vary by program and state |
| J.C. Taylor | Directly and through its own team | Agreed value collector coverage | Limited pleasure use; check program rules |
| Heacock Classic | Directly by phone and online | Agreed value; the claims team can help with salvage buyback | Up to 6,000 pleasure miles a year, per Finder |
| American Modern | Through independent agents | Agreed value, with a stated value option | Limited use; vehicle must be kept in a locked garage or building |
| Grundy | Directly | Agreed value, which Grundy says its founder invented | No mileage restrictions on its MVP program |
| American Collectors | Directly and through agents | Agreed value | Limited pleasure use; check program rules |
Sources: program websites, State Farm, and Finder, October 2026.
See our classic car insurance company comparison for details.
Documentation checklist
- Recent appraisal for higher-value cars.
- Dated photos of exterior, interior, engine bay, and undercarriage.
- Receipts for restoration work and parts.
- Records of awards, provenance, and matching numbers.
- A list and photos of stored spare parts.
Store copies off-site or in the cloud so they survive a fire or theft.
Roadside help and flatbed towing
Collector vehicles often need flatbed towing to avoid damage, and some older cars cannot be towed conventionally. Several collector programs include or offer roadside assistance designed for classic vehicles; Heacock Classic includes roadside assistance, per Finder. Check how far a program will tow and whether it covers trailers.
Seasonal storage and lay-up
Many owners store collector cars for the winter. Collector policies are usually priced for limited use already, so there is rarely a need to cancel. If you do reduce coverage during storage, keep comprehensive, which covers fire, theft, and storm damage while the car sits.
Liability and state minimums
A collector car driven on public roads must meet your state's minimum liability requirements. Many collectors choose much higher limits and add an umbrella policy, since a serious accident in any vehicle can threaten savings and other assets.
How to compare quotes
- Decide the agreed value for each vehicle, supported by photos and, for higher-value cars, an appraisal.
- Request quotes from both with the same agreed value, liability limits, uninsured motorist limits, and deductibles.
- Compare mileage limits, storage requirements, and driver rules against how you actually use the car.
- Compare extras: spare parts, roadside and flatbed towing, restoration coverage, and event coverage.
- Ask each for the legal name of the issuing insurer and its financial strength rating.
- Review the full total, including fees and any membership costs.
How to verify an insurer or agency
Before buying through any website or app, confirm who is selling you the policy and who will issue it:
- Find the licensed agency or insurer named in the site's footer, terms, or license page.
- Look up the agency or producer on your state insurance department's license search, or through the National Insurance Producer Registry (NIPR).
- Look up the insurer on your state insurance department's company search to confirm it is authorized in your state.
- Save the insurer's name and policy number once issued, since that is who handles claims.
A legitimate service will make this information easy to find. Be cautious if you cannot identify the licensed entity.
What to have ready for a classic car quote
These details help produce accurate quotes.
- Vehicle details. Year, make, model, VIN, and condition.
- Agreed value. Your estimate, supported by photos or an appraisal.
- Storage. Where and how the car is kept.
- Usage. Expected annual miles and events.
- Drivers. Licenses, records, and your regular-use vehicle.
Agreed value vs. stated value FAQs
What is agreed value?
A value set when the policy is written and paid on a covered total loss, minus any deductible.
What is stated value?
Usually a cap; the policy pays the lesser of that amount or actual cash value.
Which is better for classic cars?
Agreed value, in most cases.
Is stated value cheaper?
Often, but it may pay less.
What is actual cash value?
Market value minus depreciation.
Is guaranteed value the same as agreed value?
Similar in concept; read the policy for details.
Do I need an appraisal for agreed value?
Often for higher-value cars.
Can I change my agreed value?
Yes, usually at renewal or after documented work.
Related guides
Important information
Independent agency. Blake Insurance Group LLC is an independent insurance agency. Licensed insurance producer NPN 16117464. Licensed states: AZ, AL, TX, CA, NY, OH, FL, NC, VA, GA, OK, NM, IA, KS, MI, NE, SC, SD, WV, IL, NJ, PA, TN, and WA. Which insurance companies we can quote depends on our current appointments, the product, and your state. Mentioning a company on this page does not mean we represent it.
Collector coverage. Classic and collector programs set their own eligibility, valuation, and usage rules. The issued policy controls.
Availability. Coverage, prices, discounts, and eligibility vary by insurer, state, and applicant, and are subject to underwriting. The issued policy controls.
Availability. Coverage, prices, discounts, and eligibility vary by insurer, state, and applicant, and are subject to underwriting. The issued policy controls.
Your next step
Request a quote, and a licensed agent will compare collector car options available to us with the agreed value and limits you choose.




