Licensed Insurance Agents Compare Trusted Insurance Companies Secure & Private Online Quotes No Spam We Never Sell Your Personal Information
Talk to a licensed agent
888-387-3687
Fast Quotes • Coverage Reviews • Independent Advice
Blake Insurance Group
Modern Independent Insurance Agency
Compare coverage from trusted insurance companies with licensed agents who work for you—not a single carrier.
Skip to North Carolina auto insurance guide
Auto insurance • North Carolina • 50/100/50 limits and required UM/UIM
Start an auto quote

Liability is the legal floor. UM/UIM is part of the same floor.

North Carolina Auto Insurance

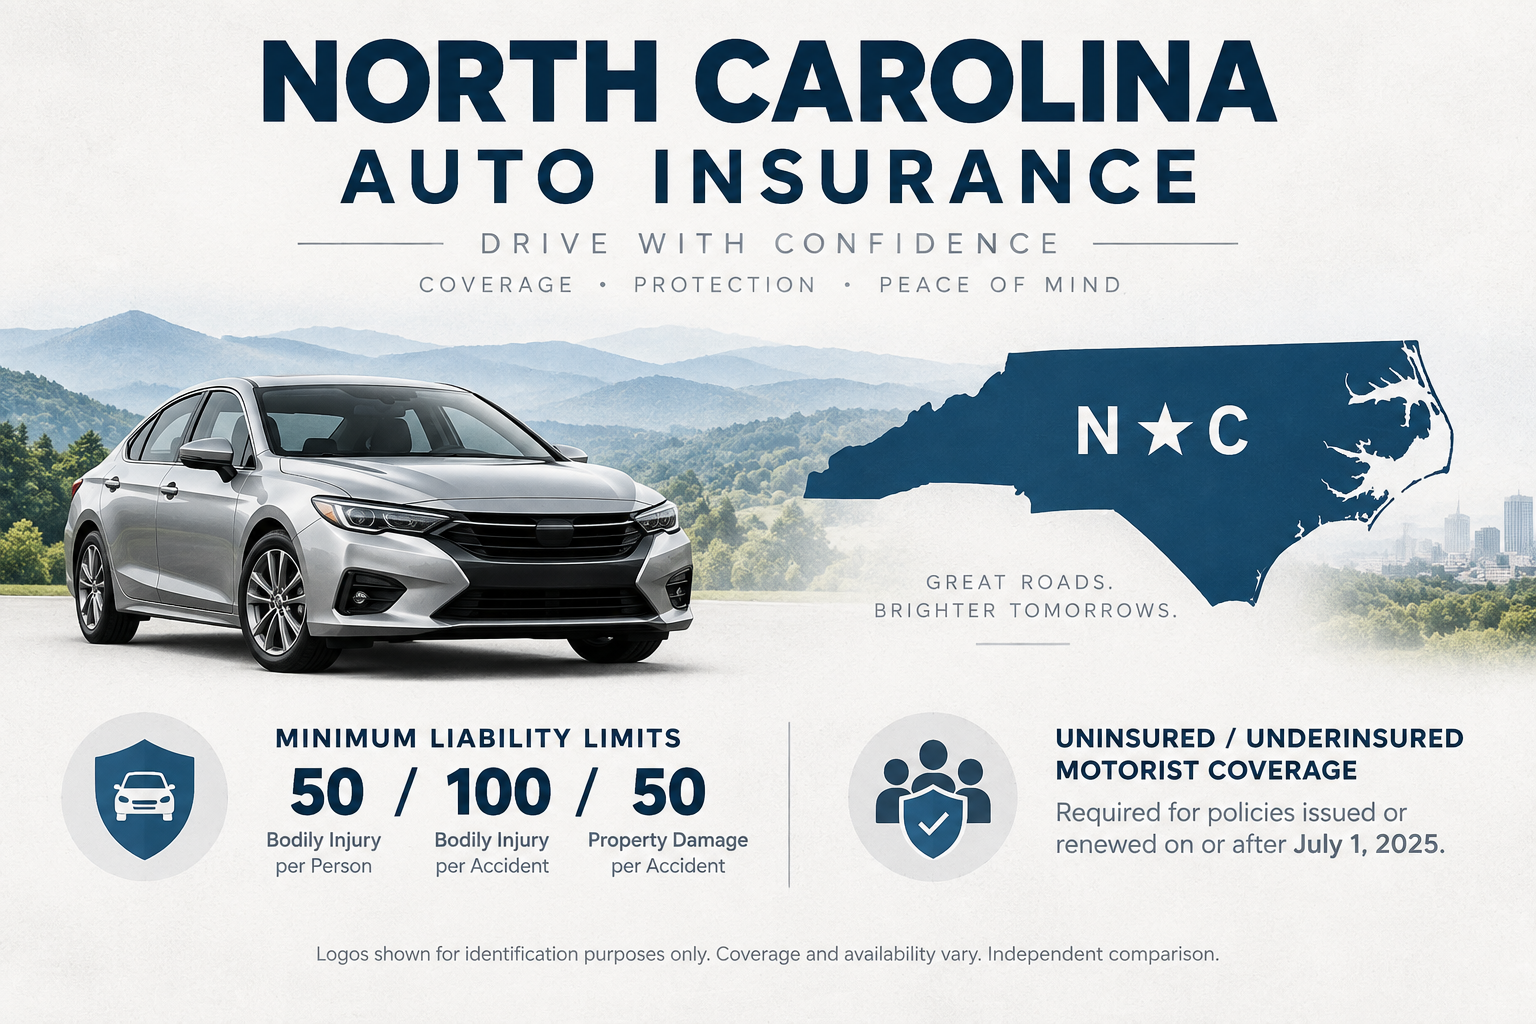
Educational graphic about North Carolina auto insurance, including liability limits, uninsured motorist coverage, and continuous registration rules.

North Carolina auto insurance is the liability policy a registered vehicle must keep in force. NCDMV requires continuous coverage from a company licensed to do business in North Carolina. Out-of-state policies are not accepted for a North Carolina registration. For policies issued or renewed on or after July 1, 2025, the minimum liability limits are $50,000 per person and $100,000 per accident for bodily injury, plus $50,000 for property damage.

Blake Insurance Group LLC is an independent insurance agency licensed in North Carolina. Licensed producers can help eligible drivers compare liability, uninsured and underinsured motorist coverage, and optional physical-damage protection. This page is not an NCDMV or Department of Insurance publication and does not create a staffed office in Charlotte, Raleigh, Greensboro, or Wilmington. Availability, underwriting, and price vary by driver, vehicle, garage ZIP, and record.

The quote button opens a Bolt quoting site used by Blake Insurance Group. That site is separate from blakeinsurancegroup.com. Submitting information does not bind coverage. Keep the current policy active until a replacement is issued.

Quick facts about North Carolina auto insurance

North Carolina is an at-fault liability state. The driver who causes a crash is responsible for other people’s injuries and property damage up to the purchased limits. The legal minimum is a floor for registration, not a prediction of what a serious crash costs.

North Carolina auto insurance at a glance
Topic What is usually true What still varies
Who must carry it Every vehicle with a valid North Carolina registration must keep continuous liability insurance. Surrender the plate to NCDMV before you cancel a policy on a vehicle you no longer intend to keep registered.
Who can write the policy The insurer must be licensed to do business in North Carolina. Out-of-state policies do not satisfy a North Carolina registration. Not every licensed company will accept every driver or vehicle.
Current minimum liability Policies issued or renewed on or after July 1, 2025 must meet 50/100/50. A policy issued before that date could still show 30/60/25 until it renewed.
UM and UIM North Carolina law also requires uninsured and underinsured motorist coverage. Higher UM/UIM limits may be available. The declarations control the purchased amount.
Collision and comprehensive The state does not require physical-damage coverage to register a vehicle. A lender or lessor typically requires collision and comprehensive until the loan or lease ends.
Blake service model Blake Insurance Group LLC is licensed in North Carolina and can assist eligible applicants by phone and online tools. A license is not a staffed North Carolina branch.

Required liability limits and uninsured / underinsured motorist coverage

NCDMV publishes the split-limit change that took effect for new and renewed policies after July 1, 2025. The North Carolina Department of Insurance separately explained that drivers previously on minimum limits should expect the renewal to include the higher required amounts, and that underinsured motorist coverage is included on new or renewed policies from that date forward.

North Carolina minimum auto liability limits published by NCDMV
Coverage part Policies issued or renewed before July 1, 2025 Policies issued or renewed after July 1, 2025
Bodily injury, one person $30,000 $50,000
Bodily injury, two or more people $60,000 $100,000
Property damage $25,000 $50,000

Those three numbers are split limits. $50,000 is the most the policy will pay for one injured person. $100,000 is the most it will pay for all injured people in one accident. $50,000 is the most it will pay for other people’s property. A two-car wreck with hospital bills and a late-model SUV can exhaust 50/100/50 quickly. Higher limits such as 100/300/100 or an umbrella sitting over auto and home are optional purchases, not a state mandate.

Uninsured motorist (UM)

UM can respond when the at-fault driver has no liability insurance or cannot be identified, including many hit-and-run facts, subject to the policy. North Carolina also writes uninsured motorist property damage with its own deductible on many forms.

Underinsured motorist (UIM)

UIM can respond when the at-fault driver has insurance, but not enough insurance for the injuries. DOI materials note that the 2025 legislation also changed how an underinsured vehicle is measured and limited certain setoffs. Read the declarations rather than assuming the old stacking story still applies.

G.S. 20-279.21 is the Financial Responsibility Act section NCDMV cites for both the liability floor and the UM/UIM requirement. The requirement applies even when you buy limits above the minimum. Matching UM/UIM to the liability you actually carry is the usual way to keep the household protected when the other driver bought only the legal floor.

Continuous coverage, plate surrender, and NCDMV lapse notices

North Carolina does not treat auto insurance as a one-time sticker. Insurers must notify NCDMV when required liability is canceled or lapses. NCDMV then sends a liability insurance termination notice to the registered owner. The owner has a short window to show that coverage is back in force or that the plate has been surrendered. NCDMV currently describes a 10-day response period and states that, effective October 1, 2026, the response window becomes 30 days. Missing the notice can lead to plate revocation, civil penalties, late fees, interest, and collections.

Cancel the plate first, then the policy. NCDMV tells owners not to cancel insurance until the license plate has been surrendered. Ending a policy while the vehicle is still registered is how a clean driving record still produces a lapse letter.

Proof of insurance should travel with the vehicle. Digital ID cards are commonly accepted when they show the current term, vehicle, and named insured, but the officer or clerk still needs a readable card. After a carrier change, wait for the new card before you shred the old one. A binder is not the same as a processed NCDMV record if the prior insurer already sent a cancellation.

Some drivers also need an SR-22 or similar financial-responsibility filing after a conviction or license action. That filing is a certificate the insurer sends to the state. It is not extra crash coverage. If the underlying policy lapses, the filing fails with it. Ask whether the quote includes the required filing before you treat the premium as complete.

Coverages that are common but not the North Carolina legal minimum

“Full coverage” is not a statute. In conversation it usually means liability plus collision and comprehensive. Those physical-damage parts are optional under state law and often mandatory under a loan. Medical payments, rental reimbursement, roadside, custom-parts coverage, and accident forgiveness are product features, not registration requirements.

Collision

Pays to repair your vehicle after a crash with another object, subject to the deductible, even when you are at fault. It does not replace liability owed to the other party.

Comprehensive

Addresses many non-collision losses such as theft, vandalism, fire, falling objects, and some weather events, subject to the deductible and exclusions. Flood to a parked car is a comprehensive question, not a liability question.

Medical payments and extras

Med Pay can help with occupant medical bills regardless of fault, up to a small selected limit. Rental and roadside are convenience coverages. None of them replace UM/UIM or health insurance.

North Carolina also operates a residual market for drivers the voluntary market declines. Placement through the North Carolina Reinsurance Facility, when it applies, is a last-resort mechanism overseen through the state’s residual-market structure. It is not a discount program and not a Blake product. A producer can tell you whether a quoted policy is voluntary-market or residual-market paper.

What actually changes a North Carolina auto insurance quote

There is no honest statewide “average premium” that belongs on your declarations page. North Carolina uses a regulated rating environment that still leaves room for company underwriting, household composition, and vehicle risk. A cheaper quote can be a thinner contract: a higher deductible, missing rental coverage, or liability left at the legal floor.

  • Garage ZIP and how the vehicle is used: commute, pleasure, farm, or business.
  • Annual mileage and whether the car is garaged or street-parked.
  • Driver ages, licensed years, and household members who have access to the keys.
  • Accidents, violations, and lapse history.
  • Vehicle year, value, safety features, and theft profile.
  • Chosen liability and UM/UIM limits, plus collision and comprehensive deductibles.
  • Good-student, multi-car, multi-policy, paperless, and pay-in-full discounts when the insurer actually offers them.
  • Need for an SR-22 or similar filing.

Compare quotes on the same drivers, the same VINs, and the same limits. A minimum-liability price next to a 100/300 quote with $500 deductibles is not a savings contest. It is two different products.

How to request a North Carolina auto insurance quote

People searching for auto insurance near me in North Carolina usually need a licensed producer who can keep liability continuous through a carrier change, not a storefront on every corner. Start the Bolt form or call 888-387-3687. Agency hours are listed as Monday through Friday, 9:00 a.m. to 5:00 p.m.

  1. Driver names, dates of birth, and license numbers for everyone in the household who drives.
  2. VINs, use of each vehicle, and overnight parking ZIP.
  3. Current carrier, expiration date, and whether any vehicle is financed or leased.
  4. Desired liability and UM/UIM limits, not only “state minimum.”
  5. Collision and comprehensive deductibles if physical damage is needed.
  6. Any SR-22, out-of-state license, or recent lapse letter from NCDMV.

Coverage starts when an insurer issues a binder or policy and the required premium is paid. Ask the producer to confirm that the new insurer will report coverage to NCDMV before the old policy is canceled. If you are dropping a vehicle, surrender the plate first.

Related Blake Insurance Group guides

North Carolina auto insurance FAQs

Is auto insurance required in North Carolina?

Yes, for a vehicle with a valid North Carolina registration. Coverage must be continuous and written by a company licensed in North Carolina. Out-of-state policies do not satisfy that registration rule.

What are the current minimum limits?

For policies issued or renewed on or after July 1, 2025, NCDMV lists $50,000 bodily injury per person, $100,000 bodily injury per accident, and $50,000 property damage. Older terms could still show 30/60/25 until they renewed.

Is uninsured motorist coverage required?

Yes. North Carolina law requires uninsured and underinsured motorist coverage in addition to the liability floor. Confirm the limits printed on your declarations.

What happens if my policy lapses?

The insurer notifies NCDMV. You receive a termination notice and must respond within the published window—currently described as 10 days, moving to 30 days effective October 1, 2026—or risk plate revocation and penalties.

Do I need collision and comprehensive?

The state does not require them to register the vehicle. A lender usually does. Without them, damage to your own car after a crash, theft, or hail event is a personal expense.

Does Blake Insurance Group have a North Carolina auto office?

This page does not describe a staffed North Carolina branch. The agency is licensed in North Carolina and assists eligible clients by phone and online tools.

What happens after I click the quote button?

You leave this page and open a Bolt quoting workflow used with source code BLAKEINSURANCEGROUP. That third-party site collects driver and vehicle details to start a comparison. It does not guarantee a price, a carrier, or a bindable policy.

Meet the legal floor, then decide if the floor is enough

Start with 50/100/50 and the required UM/UIM. Decide whether your assets and the cars in your driveway need higher liability and physical-damage deductibles you can actually pay. Then request a quote and keep the current policy live until the replacement is in force. Call 888-387-3687 Monday through Friday, 9:00 a.m. to 5:00 p.m.

Important information

Independent agency. Blake Insurance Group LLC is an independent insurance agency. It is not an insurance company, NCDMV, the North Carolina Department of Insurance, or the North Carolina Rate Bureau. It does not represent every insurer or every driver in every county. Brand names are trademarks of their owners. No appointment, endorsement, ranking, or partnership should be inferred from this page.

Availability. Eligibility, forms, deductibles, UM/UIM options, physical-damage coverage, residual-market placement, discounts, and premiums vary by insurer, driver, vehicle, and underwriting. This page does not publish a personal premium.

Official resources. NCDMV insurance requirements are at ncdot.gov/dmv. The North Carolina Department of Insurance consumer line is 1-855-408-1212.

Third-party quote site. Buttons labeled “Start an auto quote” open Bolt at d2capi.boltinc.com with source BLAKEINSURANCEGROUP. That site’s privacy practices, accessibility, product menu, and terms apply. Submitting information does not bind coverage or guarantee approval, a rate, or an effective date.

Licensing. Licensed insurance producer NPN 16944666. Licensed states currently listed by the agency include Alabama, Arizona, California, Florida, Georgia, Illinois, Iowa, Kansas, Michigan, Nebraska, New Jersey, New Mexico, New York, North Carolina, Ohio, Oklahoma, Pennsylvania, South Carolina, South Dakota, Tennessee, Texas, Virginia, Washington, and West Virginia. Confirm current authority for the coverage requested. A state license does not create a physical office in that state. Principal agent: Blake Nwosu.

Published by Blake Insurance Group LLC. Page rewritten September 21, 2026 to replace mismatched renters-insurance content on this URL and to align North Carolina auto facts with current NCDMV and Department of Insurance materials. Recheck declarations and registration status before you cancel a policy.

Blake Insurance Group
Call: (888) 387-3687 Email: info@blakeinsurancegroup.com Mon–Fri 9:00–5:00
Blake Nwosu, Owner and Principal Agent
Blake Nwosu Owner & Principal Agent

Expert in personal and commercial insurance, including auto, home, business, health, and life insurance.

License: 16117464

Bio: blakeinsurancegroup.com/blake-nwosu/

★★★★★ Google reviews Loading…
Share: Facebook icon X (Twitter) icon LinkedIn icon Email icon



