Chevrolet Cobalt • 2005 to 2010 compact • Liability vs. full coverage
Chevrolet Cobalt Insurance: Liability vs. Full Coverage
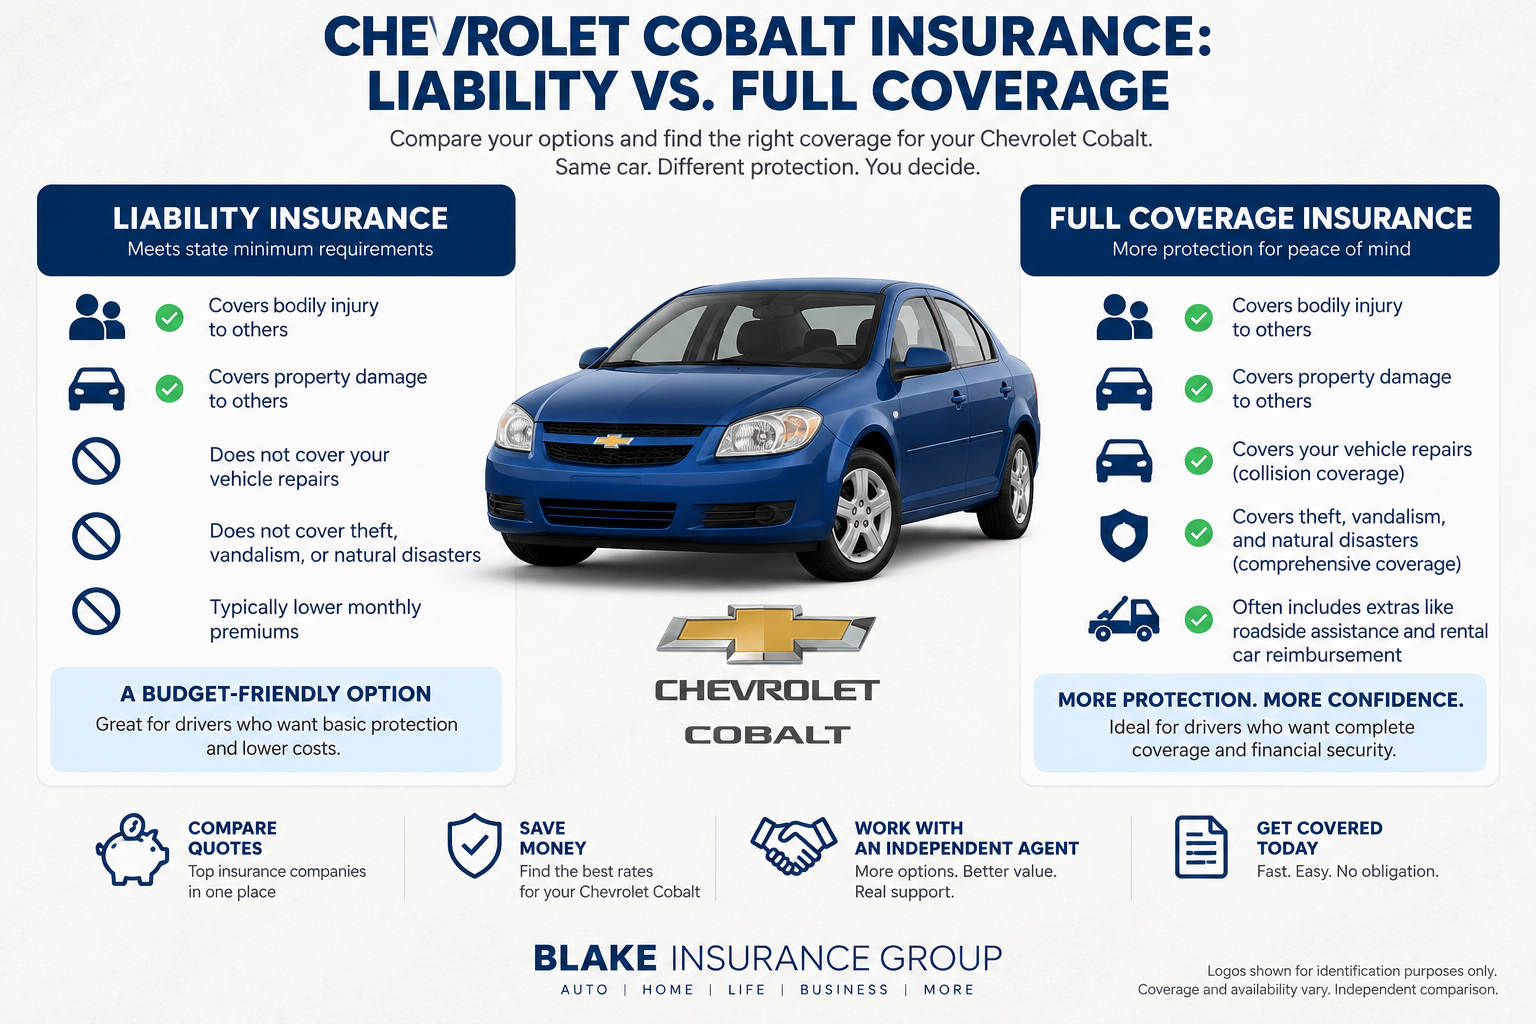
Chevrolet Cobalt insurance decisions usually come down to one question: is full coverage still worth it on a car that was last built for the 2010 model year? For many Cobalt owners, liability-only coverage makes financial sense, but the right answer depends on what your car is worth, what you could afford to replace, and whether you still owe money on it.
This guide explains the difference between liability and full coverage, walks through a simple way to decide, covers the Cobalt's ignition switch recall, and lists ways to keep costs low. Blake Insurance Group is an independent agency that can compare several insurance companies for many drivers of older cars.
Get a Chevrolet Cobalt insurance quote
Tell us about your Cobalt and whether you want liability-only or full coverage, and a licensed agent will follow up with options. Submitting the form does not bind coverage.
If the form does not load, call 888-387-3687, Monday through Friday, 9:00 to 5:00, or email info@blakeinsurancegroup.com.
Liability vs. full coverage: what each pays for
The terms can be confusing, so here is what each option generally includes. Exact coverage depends on your state and policy.
| Situation | Liability-only | Full coverage |
|---|---|---|
| You cause a crash that injures someone | Covered up to your bodily injury limit | Covered up to your bodily injury limit |
| You damage another car or property | Covered up to your property damage limit | Covered up to your property damage limit |
| Your Cobalt is damaged in a crash you caused | Not covered | Covered by collision, minus your deductible |
| Your Cobalt is stolen, vandalized, or hit by hail or a falling tree | Not covered | Covered by comprehensive, minus your deductible |
| An uninsured driver hits you | Depends on whether you carry uninsured motorist coverage | Depends on whether you carry uninsured motorist coverage |
Full coverage is not a legal term. It usually means liability plus collision and comprehensive, and many drivers also add uninsured motorist coverage.
Learn more on our liability-only car insurance and full coverage car insurance pages.
How to decide if full coverage is still worth it
Collision and comprehensive pay the car's actual cash value after a total loss, which is what a similar car in similar condition was worth just before the loss, minus your deductible. For an older Cobalt, that payout may be modest. A simple way to decide:
- Estimate your Cobalt's value. Use a pricing guide with your exact year, trim, mileage, and condition, or compare local listings.
- Subtract your deductible. That is roughly the most you would receive if the car were totaled.
- Find out what collision and comprehensive cost per year. Ask your agent for the price with and without them.
- Compare. If you would pay a large share of the possible payout in premiums each year, liability-only may make more sense.
- Ask yourself one more question. If the Cobalt were wrecked tomorrow, could you afford to replace it? If not, keeping physical damage coverage may still be worth it.
Illustrative example: if a Cobalt is worth about $3,000 and you have a $500 deductible, the most a total-loss claim would pay is about $2,500. If collision and comprehensive add several hundred dollars a year, you would be paying a meaningful share of that amount each year for the protection. These figures are an example only, not a quote or a typical price.
Remember that liability coverage is required in nearly every state, and some states also require uninsured motorist coverage or personal injury protection. Dropping collision and comprehensive never removes those requirements. Our car insurance deductible calculator can help you test different deductibles.
Middle-ground options
You do not have to choose between all or nothing. Consider:
- Comprehensive only. Some insurers let you keep comprehensive without collision. It is usually inexpensive and protects against theft, hail, flooding, fire, and animal strikes.
- Higher deductibles. Raising deductibles to $1,000 or more lowers the cost of physical damage coverage while keeping protection against a total loss.
- Keep uninsured motorist coverage. If an uninsured driver hits you, uninsured motorist property damage or collision coverage may help, depending on your state.
- Add roadside assistance. On an older car, towing and jump-starts can be more useful than collision coverage. See our roadside assistance page.
The Cobalt ignition switch recall
In 2014, General Motors recalled Cobalts and several other vehicles because the ignition switch could move out of the run position under certain conditions, shutting off the engine and disabling power steering, power brakes, and airbag deployment. GM linked the defect to numerous crashes and deaths.
If you own a Cobalt, check whether the recall repair has been completed by entering your VIN on NHTSA's recall lookup or contacting a Chevrolet dealer. Recall repairs are free. An unrepaired safety recall does not usually change your premium directly, but it affects your safety and could complicate matters after a crash. Until the repair is done, GM advised owners to use only the ignition key with nothing else on the key ring.
Insuring a Cobalt SS
The Cobalt SS was the performance version, with a supercharged engine in early years and a turbocharged engine in later years. Insurers typically rate the SS higher than a standard Cobalt because of its power. Some SS models, particularly well-kept turbocharged cars, have enthusiast value above a typical Cobalt.
If your SS is modified, disclose the changes and ask about custom equipment coverage. Standard policies pay actual cash value, which may not reflect what an enthusiast would pay. Some specialty insurers offer agreed-value coverage for collectible or enthusiast vehicles, but eligibility usually depends on age, limited use, and storage. Our classic auto insurance page explains how those policies generally work.
Ways to save on Cobalt insurance
- Match coverage to the car's value using the steps above.
- Keep liability limits strong. Saving on the car makes sense; cutting liability exposes your savings and future income.
- Compare several insurers. Older-car pricing varies by company.
- Ask about discounts for safe driving, paying in full, autopay, low mileage, and bundling.
- Consider telematics if you drive carefully.
- Review your policy each renewal as the car's value continues to change.
- Maintain continuous coverage. Even on an inexpensive car, a lapse in insurance can raise your rates on future vehicles.
- Consider dropping rental reimbursement if you have another car available, since its value is limited on a liability-only policy.
A Cobalt as a first car
Older, inexpensive cars like the Cobalt are common first cars. A low purchase price makes liability-only coverage tempting, and for many families it is reasonable. Keep in mind that a Cobalt lacks modern driver-assistance features such as automatic emergency braking, and safety designs have improved considerably since it was built. If a teen will drive a Cobalt, make sure the ignition recall is completed, carry strong liability limits, and ask about good student and driver training discounts. Our guide to insurance for a new driver has more ideas.
What you need for a Cobalt insurance quote
These details help us quote both liability-only and full coverage so you can compare.
- VIN, model year, and trim. This confirms sedan or coupe and whether the car is an SS.
- An estimate of the car's value. Helps decide whether collision and comprehensive are worth it.
- Loan status. If the Cobalt is financed, the lender will require full coverage.
- Drivers and history. Dates of birth, license numbers, and recent accidents or violations.
- Current declarations page. To compare your current coverage with new options.
Chevrolet Cobalt insurance FAQs
Should I get liability or full coverage on my Cobalt?
It depends on the car's value, the cost of collision and comprehensive, and whether you could afford to replace it. Many owners of older Cobalts choose liability-only, but compare both prices first.
What does full coverage mean?
It usually means liability plus collision and comprehensive. It is not a legal term, so check exactly which coverages a quote includes.
Can I keep comprehensive but drop collision?
Many insurers allow it. Comprehensive is usually inexpensive and covers theft, weather, fire, and animal strikes.
Does the ignition switch recall affect my insurance?
It does not usually change your premium, but you should get the free repair for safety. Check your VIN on NHTSA's recall lookup.
Is a Cobalt SS more expensive to insure?
Usually, because it is the performance version. Modified SS models may need custom equipment coverage.
Do I need full coverage if I still owe money on my Cobalt?
Yes, lenders typically require collision and comprehensive until the loan is paid off.
What happens if my Cobalt is totaled?
With collision or comprehensive, the insurer pays the car's actual cash value minus your deductible. With liability-only, you receive nothing for your own car.
Is the Cobalt expensive to insure?
For a standard Cobalt, usually not, especially with liability-only coverage. The SS, young drivers, and your driving record can raise the price.
Does my Cobalt need uninsured motorist coverage?
It is a good idea on any car, and some states require it. It protects you and your passengers if a driver with little or no insurance causes a crash, which matters even when the car itself is worth little.
Related vehicle insurance guides
These guides cover closely related vehicles and situations:
Important information
Independent agency. Blake Insurance Group LLC is an independent insurance agency. Licensed insurance producer NPN 16117464. Licensed states: AZ, AL, TX, CA, NY, OH, FL, NC, VA, GA, OK, NM, IA, KS, MI, NE, SC, SD, WV, IL, NJ, PA, TN, and WA. Which insurance companies we can quote depends on our current appointments and your state.
Trademarks. Chevrolet, Chevy, and Cobalt and the insurance company names and logos shown in the image on this page are trademarks of their respective owners and are used for identification only. Blake Insurance Group is not affiliated with or endorsed by any vehicle manufacturer, and the logos do not mean we represent, partner with, or are endorsed by those insurance companies.
Independent comparison. Vehicle details on this page come from manufacturer and public safety sources and can change by model year and trim. Our explanations of how those details may affect insurance are general and are not a quote. Premiums, discounts, and eligibility vary by insurer, state, driver, vehicle, and coverage, and are subject to underwriting. The issued policy controls.
Your next step
Estimate your Cobalt's value, gather your VIN and current policy, and request quotes for both liability-only and full coverage. We will help you compare the difference so you can decide with real numbers.




