Dental insurance guide
How Much Is Dental Insurance?
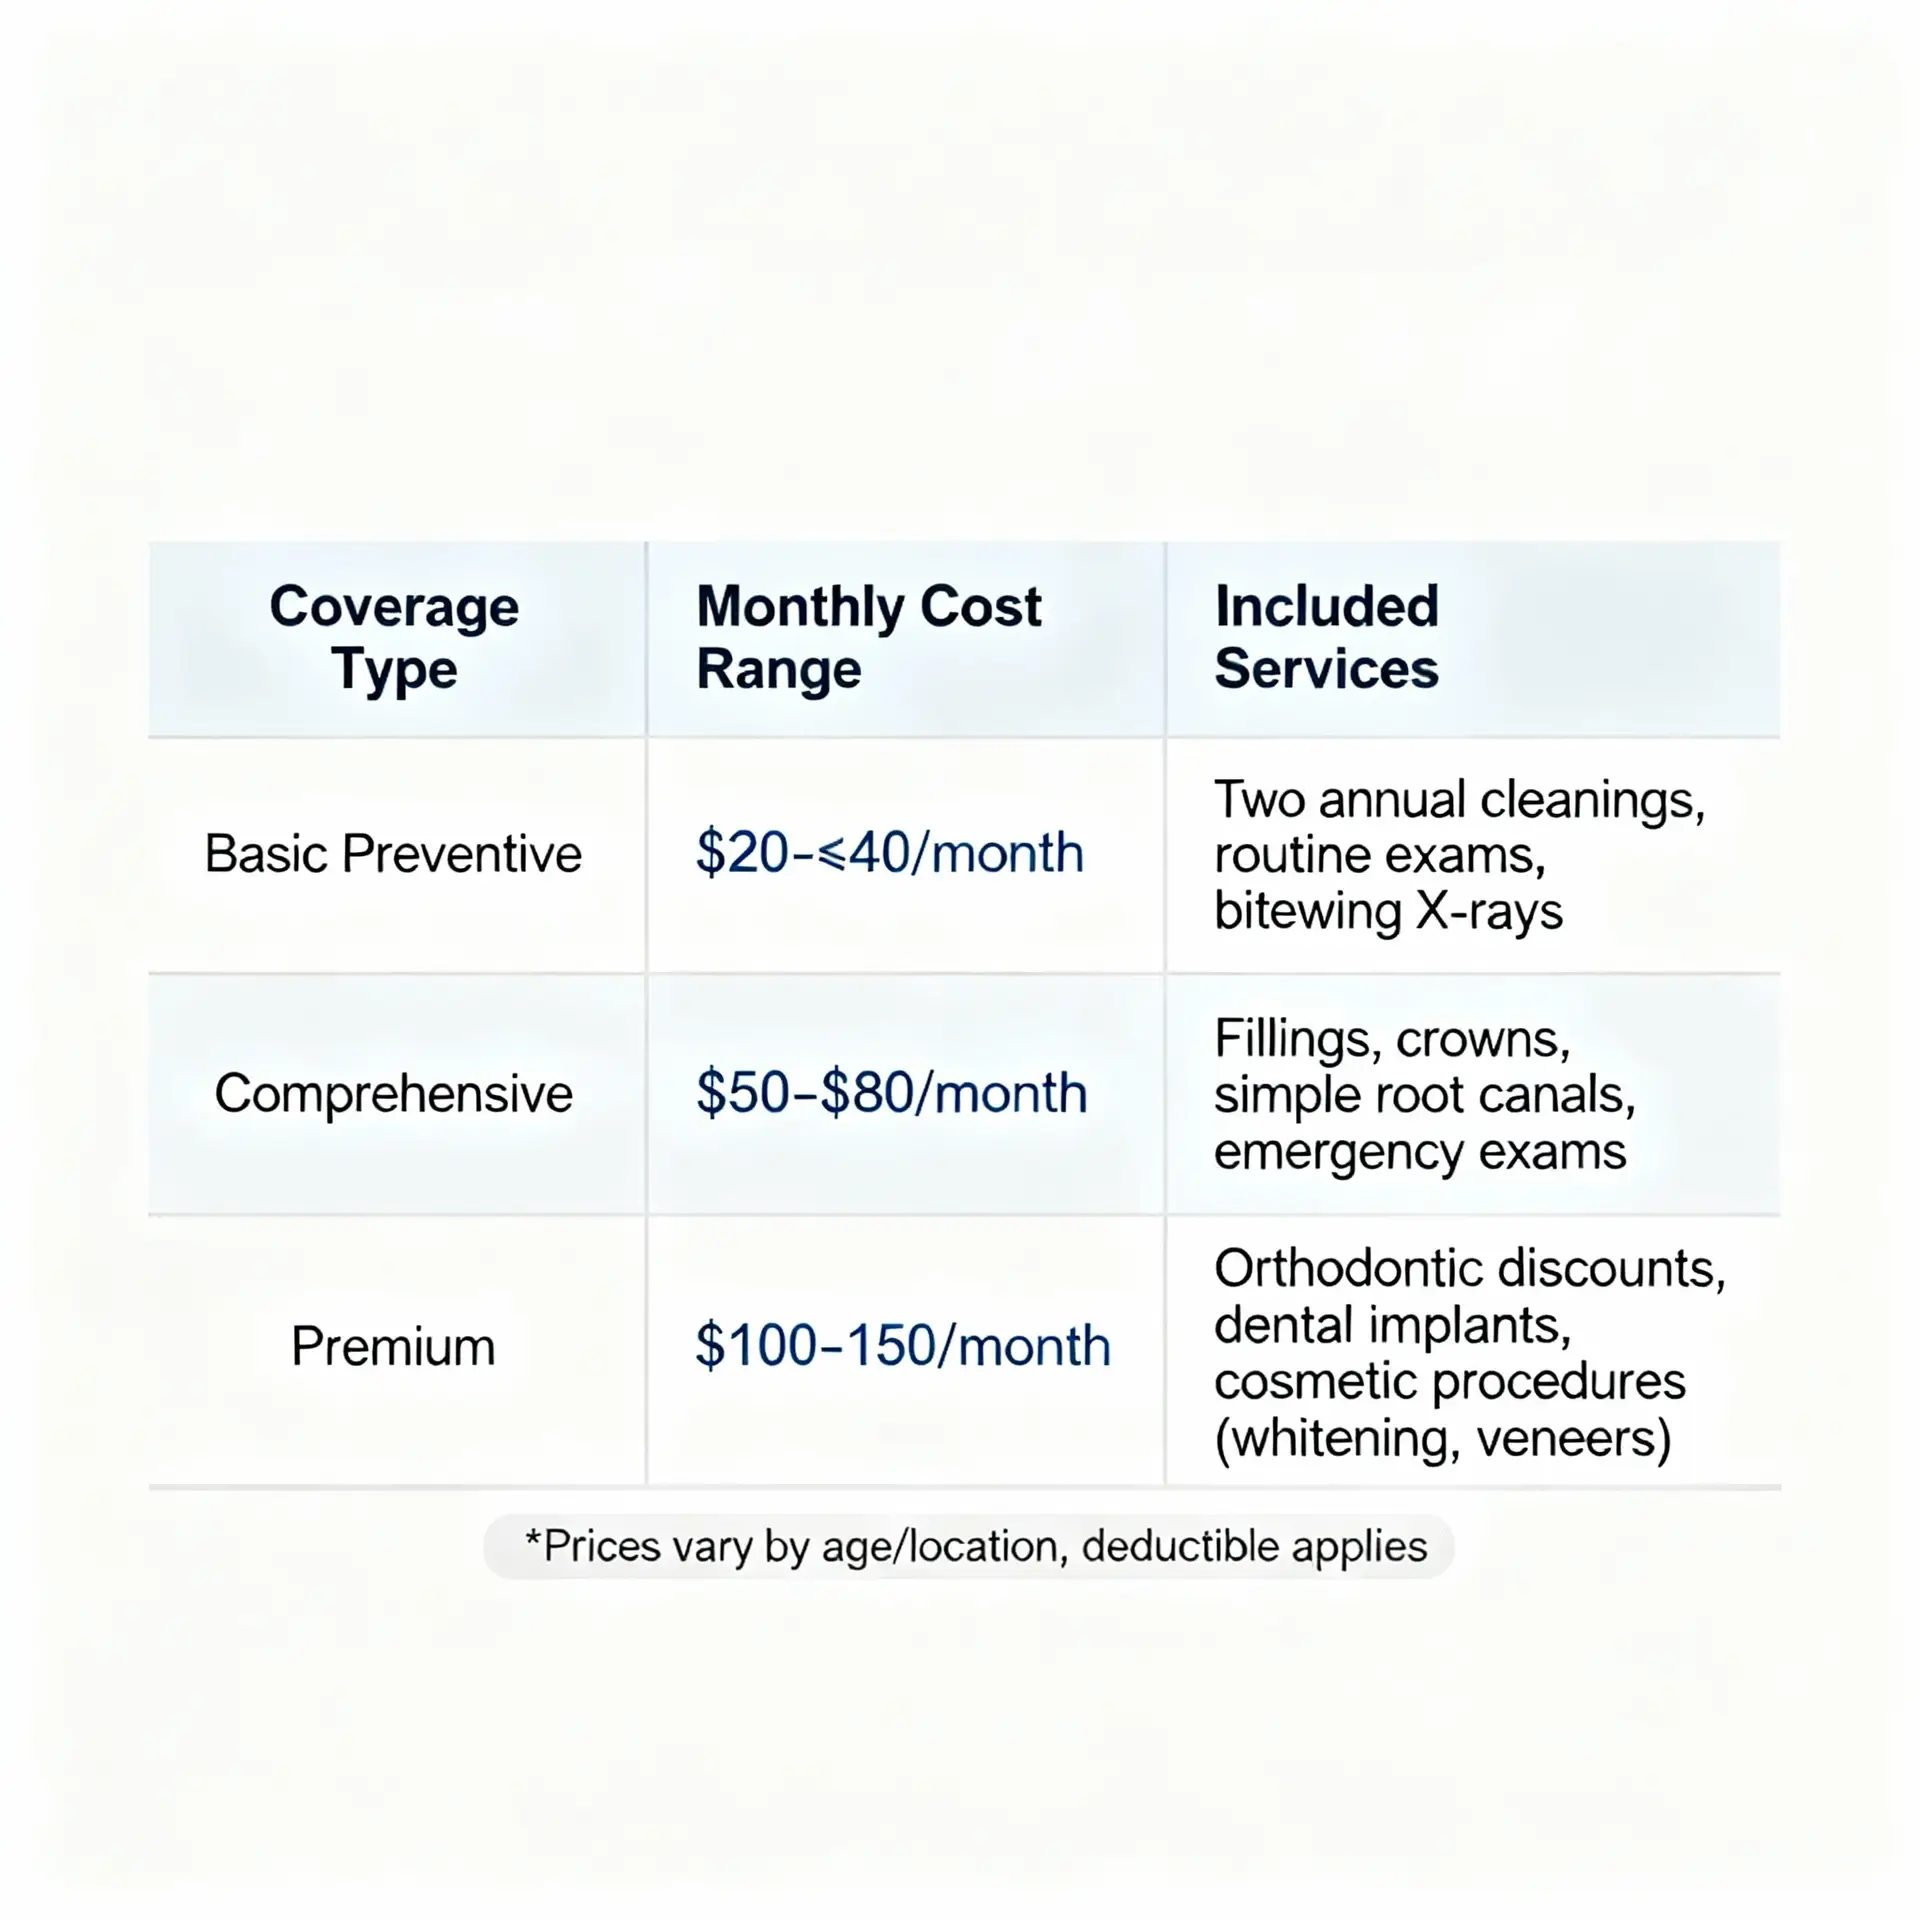
How much is dental insurance? Published individual plans start around $18 to $30 a month, but your real cost also includes deductibles, coinsurance, and anything above the annual maximum. Here’s how to estimate the full yearly cost.
Blake Insurance Group is an independent agency serving clients by phone, email, and online in states where we are licensed; coverage depends on the insurer, the policy, and underwriting.
Request dental insurance quotes
Tell us what you would like to cover, and a licensed agent will follow up with options available to us. Submitting the form does not bind coverage.
If the form does not load, call 888-387-3687, Monday through Friday, 9:00 to 5:00, or email info@blakeinsurancegroup.com.
Published starting prices
| Plan or program | Published price | Type |
|---|---|---|
| Ameritas PrimeStar Lite dental | About $30.46 a month (U.S. average) | Insurance |
| Ameritas PrimeStar Complete dental | About $66.58 a month (U.S. average) | Insurance |
| Humana individual dental | From $18 a month | Insurance |
| Careington Care 500 Series | $184.95 a year plus a $20 fee | Discount plan, not insurance |
| Aetna Vision Preferred (Value) | From $11 a month | Insurance |
| Guardian individual vision (Standard, FL) | From $12 a month | Insurance |
| EyeMed individual (Healthy / Bold / Bright) | From $5.00 / $17.50 / $30.00 a month in most states | Healthy gives eyewear discounts; Bold and Bright are insurance |
Sources: company websites and an authorized Careington marketer, checked October 2026. Prices vary by age, state, and plan; get a quote for your ZIP code.
What affects the price
Dental and vision premiums depend mostly on where you live, who is covered, the plan type, and the benefit level. A higher annual maximum, lower coinsurance for major care, no waiting periods, or orthodontic coverage usually means a higher premium. For vision, larger frame and contact allowances, lower exam copays, and 12-month instead of 24-month frequency cost more. Family plans cost more than individual plans, but per person they can be cheaper than buying separate policies.
Estimating your total yearly cost
Add 12 months of premium to the deductible and your share of the care you expect. For example, on a plan that pays 80% for basic care after a $50 deductible, a $200 filling would cost you $50 plus 20% of the remaining $150, or $80, on top of premiums. Major care paid at 50% can reach the annual maximum quickly. Compare that total with paying your dentist directly or using a discount plan.
Types of dental plans
| Type | How it works |
|---|---|
| Dental PPO (DPPO) | Insurance with a network of dentists at set fees; you can usually go out of network for less coverage |
| Dental HMO (DHMO) | Contracted dentists are prepaid per member; you generally must use a contracted office; often no annual maximum |
| Indemnity | Pays a percentage of charges, often capped at usual and customary fees; any dentist |
| Discount or savings plan | Not insurance: you pay discounted fees directly to participating dentists |
Sources: American Dental Association and NAIC consumer guidance.
How dental coverage works
Many dental insurance plans use a 100/80/50 structure: preventive care such as cleanings, exams, and X-rays at 100%, basic care such as fillings at 80%, and major care such as crowns, bridges, and dentures at about 50%, after a deductible. Insurers differ on where root canals and other services fall. Typical deductibles are about $50 per person, and preventive care is usually covered before the deductible.
Most plans cap what they pay each year. Insurer guidance puts typical annual maximums at $1,000 to $2,000, and ADA News reports that maximums haven’t kept pace with inflation for decades. The ADA’s Health Policy Institute found only 3.4% of dental patients reach the typical annual maximum in a year.
What falls into each tier varies by insurer. HealthPartners describes preventive care as checkups, X-rays, cleanings, and fluoride and sealants for children; basic care as fillings, simple extractions, gum disease treatment, and often root canals; and major care as crowns, implants, bridges, dentures, and oral surgery. The NAIC notes that orthodontics usually comes as a rider, and that periodontic and prosthodontic care is often covered only in later years of a policy.
Plans also limit frequency, such as two preventive visits a year or bitewing X-rays once a year, and many require a minimum gap between cleanings. Common exclusions include cosmetic work such as whitening and veneers. Before you replace a tooth, ask whether the policy has a missing tooth clause, which can exclude replacing a tooth lost before your coverage began.
Waiting periods and limits
Waiting periods are common for basic and major services: insurer guidance puts them at about three to six months for basic care and three to 12 months for major care, while checkups and cleanings are usually covered right away. Some plans waive waiting periods if you had continuous prior coverage, and some have none. Many plans also limit how often services are covered, such as two cleanings a year, and exclude cosmetic work like whitening.
How to compare dental plans
- Start with your dentist. Check whether they’re in the plan’s network, since in-network fees and coinsurance are usually better.
- Estimate a year of care. Price the cleanings, fillings, or crowns you expect, then apply the plan’s coinsurance and deductible.
- Check the annual maximum. Major work can use up a $1,000 to $2,000 maximum quickly.
- Read the waiting periods. If you need major care soon, a plan with no waiting period may matter more than a lower premium.
- Compare with paying cash. Add the yearly premium to your share of costs and compare that with paying your dentist directly or using a discount plan.
Example: Ameritas individual dental plans
| Plan | Annual maximum (day one / after year one) | In-network coinsurance (basic / major, day one → after year one) | Average price |
|---|---|---|---|
| PrimeStar Lite | $750 / $1,500 | 50%→80% / 10%→20% | About $30.46 a month |
| PrimeStar Boost | $1,500 / $2,000 | 65%→80% / 20%→50% | About $57.61 a month |
| PrimeStar Complete | $2,500 / $3,000 | 80%→90% / 20%→50% | About $66.58 a month |
Sources: Ameritas plan page and highlight sheet. Preventive care is covered at 100% in network with no deductible; basic and major have a $50 deductible. Prices are U.S. averages; enter your ZIP code for rates. Boost adds child orthodontia; Complete adds hearing care.
Ameritas says its plans have no waiting periods in most states, that coverage can start the next day, and that its Preventive Plus feature keeps preventive care from counting against the annual maximum.
Discount plans vs. insurance
A dental discount or savings plan isn’t insurance. You pay a membership fee, then pay participating dentists a discounted fee yourself; the plan pays nothing toward your care. The NAIC’s model law for discount plans requires them to state that they are not insurance, and states such as Texas require them to register. Careington, for example, sells savings plans labeled as not insurance; its Care 500 Series is listed at $184.95 a year for an individual through an authorized marketer, with 20% to 60% off dental work, a $20 processing fee, and no availability in Vermont or Washington. Association member offers start at $8.95 a month.
Dental coverage and the ACA
Under the ACA, dental coverage is an essential health benefit for children but not for adults, according to HealthCare.gov. Children’s dental coverage must be available in a health plan or as a separate dental plan, and on HealthCare.gov you can buy a stand-alone dental plan only when you also buy a health plan. Stand-alone dental plans can have waiting periods before adult services are covered.
healthinsurance.org reports that in HealthCare.gov states you generally must enroll in a medical plan to buy a Marketplace dental plan, while some state exchanges, including New York’s, allow dental-only enrollment. It also notes that most Marketplace medical plans exclude adult dental care, that pediatric dental benefits can’t have dollar limits, and that New York bars waiting periods on adult stand-alone dental plans except for orthodontia.
Medicare and dental
Original Medicare doesn’t cover most routine dental care, such as cleanings, fillings, extractions, and dentures, and doesn’t cover routine eye exams for glasses or contacts. It does cover some dental services tied to covered treatment, glaucoma screening for people at high risk, and one pair of standard eyeglasses or contacts after cataract surgery with an implanted lens. KFF reports that 98% of individual Medicare Advantage plans offered dental benefits and 99% offered vision benefits in 2026, though dental benefits are often capped.
Dental coverage by the numbers
NADP’s latest enrollment report says nearly 284 million Americans, about 83% of the population, have some form of dental benefit, down 2.3% from the year before. Cost is still a barrier: ADA Health Policy Institute data for 2025 show 12.9% of people skipped needed dental care because of cost, compared with 5.0% for medical care, according to a Becker’s summary. CDC data show 66.7% of adults had a dental exam or cleaning in the past year.
CDC data show about one in four adults ages 20 to 44 (25.9%) have untreated cavities, and 13.2% of adults 65 and older have lost all their teeth. In the ADA Health Policy Institute data summarized by Becker’s, the share skipping dental care because of cost was 17.0% for adults 19 to 64, 10.9% for adults 65 and older, and 3.8% for children.
Checking a plan and insurer
- Network. Confirm your dentist or eye doctor is in network.
- Waiting periods. Check when basic and major care are covered.
- Annual maximum. Compare it with the care you expect.
- Insurance or discount. Know which one you’re buying.
- Exclusions. Look for missing-tooth clauses, frequency limits, and cosmetic exclusions.
What an independent agency does
An independent insurance agency is licensed to sell policies from several insurance companies. Instead of quoting one company's products, an independent agent can compare options from the insurers the agency represents, explain the differences in coverage, and help you re-shop at renewal. The insurance company, not the agent, makes underwriting and claim decisions.
Blake Insurance Group is an independent agency. We work with clients by phone, email, and online in states where we are licensed, and we will tell you which insurers we can quote for your situation.
How we work
Blake Insurance Group serves clients by phone, email, and online in states where we are licensed. The insurers and plans we can offer depend on our appointments and your location; a company named on this page may not be available through us.
How to verify an insurer or agency
Before buying through any website or app, confirm who is selling you the policy and who will issue it:
- Find the licensed agency or insurer named in the site's footer, terms, or license page.
- Look up the agency or producer on your state insurance department's license search, or through the National Insurance Producer Registry (NIPR).
- Look up the insurer on your state insurance department's company search to confirm it is authorized in your state.
- Save the insurer's name and policy number once issued, since that is who handles claims.
A legitimate service will make this information easy to find. Be cautious if you cannot identify the licensed entity.
Sources
We checked the facts on this page against the sources below in October 2026. Plans, prices, and rules change, so confirm current terms before you buy.
- ADA: Types of dental plans
- NAIC: Understanding your dental insurance (2018)
- HealthPartners: How dental insurance works (Oct. 2025)
- Humana: What dental insurance covers (Feb. 2026)
- ADA News: Annual maximums (Dec. 2025)
- NAIC: Discount Medical Plan Organization Model Act
- NADP: 2025 dental benefits enrollment report (Feb. 2026)
- Becker's Dental Review: ADA HPI cost barrier data (Oct. 2026)
- CDC FastStats: Oral and dental health (June 2026)
- HealthCare.gov: Dental coverage in the Marketplace
- healthinsurance.org: Dental coverage through the Marketplace (Apr. 2026)
- Medicare.gov: Dental services
- KFF: Medicare Advantage 2026 spotlight
- Ameritas: Dental plans for individuals
- Ameritas: PrimeStar dental highlight sheet
- Ameritas: Preventive Plus
- Careington: Savings plans
- DentalPlans.com: Careington Care 500 Series (Oct. 2026)
- UHOne: UnitedHealthcare individual plans
- Humana: Dental insurance
What to have ready for a dental quote
These details help an agent quote accurately.
- Who needs coverage. Names and dates of birth.
- Your dentist or eye doctor. To check networks.
- Expected care. Cleanings only, or crowns, implants, or orthodontics.
- Current coverage. Any employer, Medicare, or other plan.
- ZIP code. Plans and prices vary by state.
Dental insurance costs FAQs
How much does dental insurance cost a month?
Published individual prices we found start around $18 to $30 a month; your price depends on your state, age, and plan.
Is a discount plan insurance?
No. You pay discounted fees directly; the plan pays nothing toward care.
Can I get coverage with no waiting period?
Some plans have none; Ameritas says its plans have no waiting periods in most states.
Is dental insurance worth it?
It depends on the care you expect. Compare a year of premiums and cost sharing with paying out of pocket.
Related guides
Partner quote options
Sponsored
Blake Insurance Group works with the partners below. Each link opens the partner's own website, where its terms, eligibility rules, and privacy policy apply. Blake Insurance Group may be compensated if you buy through these links.
- UnitedHealthcare plans (UHOne): Quotes for short-term medical, dental, vision, accident, critical illness, hospital indemnity, and other plans, depending on your state.
- Ameritas individual dental, vision, and hearing: Individual dental plans, with vision coverage and hearing care options, subject to state availability.
- Careington dental and health savings plans: Discount savings plans for dental, vision, and other care. These plans are not insurance.
Important information
Compensation. Links in the partner section of this page are sponsored, and Blake Insurance Group may be paid if you make a purchase. Sponsored placement does not affect the other information on this page.
Independent agency. Blake Insurance Group LLC is an independent insurance agency. Licensed insurance producer NPN 16117464. Licensed states: AZ, AL, TX, CA, NY, OH, FL, NC, VA, GA, OK, NM, IA, KS, MI, NE, SC, SD, WV, IL, NJ, PA, TN, and WA. Which insurance companies we can quote depends on our current appointments, the product, and your state. Mentioning a company on this page does not mean we represent it.
Plan details. Plan features and prices on this page were checked against the listed sources in October 2026 and can change. Confirm current terms with the insurer. Discount plans are not insurance.
Coverage terms. Descriptions are general. The policy contract controls what is covered.
Availability. Coverage, prices, and eligibility vary by company, state, and applicant, and are subject to underwriting. The issued policy controls.
Your next step
Request a quote, and a licensed agent will compare dental options available to us where you live.




